Industry insurance · Childcare
Brisbane-based, Australia-wide brokers for long day care, preschools, outside school hours care and family day care. Tell us about your service, your premises and your daily activities.
Childcare insurance at a glance
Injury and care claims.
Supervision and care plans.
Building, fitout and play gear.
Income after damage.
The basics
Approved services must hold public liability insurance under the National Regulations, unless a government indemnity applies. Public liability alone won’t cover your building, your income or claims about professional care.
Insurers look at your service type, approved places, age groups, premises, excursions, transport, staffing and child-safety procedures.
Supervision, plans and medication.
Building, kitchen and playground.
Staff, records and families.
Cover built around your service.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Educators caring for children at home or a venue. Start with public liability.
Cover options
Most services need a mix, not every policy. Your broker helps you choose what fits.
Injury to children or visitors and damage to others’ property.
Income and costs while the centre can’t open after insured damage.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us about your service.
What we ask
Two services of the same size can be very different risks. These details shape your cover.
01
Long day care, OSHC or family day care.
02
Capacity and age groups.
03
Owned, leased or shared.
04
Outings, swimming and transport.
05
Staff, volunteers and screening.
06
Child safety and care plans.
Running regular excursions or transport? Tell your broker before they start.
Contract requirements
Landlords, schools and councils often ask for proof of cover. The agreement may name limits and who insures what.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From business clients
What our clients say, in their own words.
Illustrative example · Childcare
Illustrative example, not a real client. An outside school hours care provider at one school starts a vacation care program with weekly excursions and a hired bus.
We would check the excursions and transport are disclosed, the school’s insurance terms, and the PI and abuse cover sections.
The new program and excursions are covered before the holidays.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Daniel and his team were fantastic. They responded quickly, truly listened to our needs, and always acted in our best interest.”
“Priority are always proactive with all our policies, always getting the best price. Love their work.”
“Easy to deal with. Promptly sent me through an insurance proposal for my new business within a day.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your service type, places, premises, activities and current policies.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
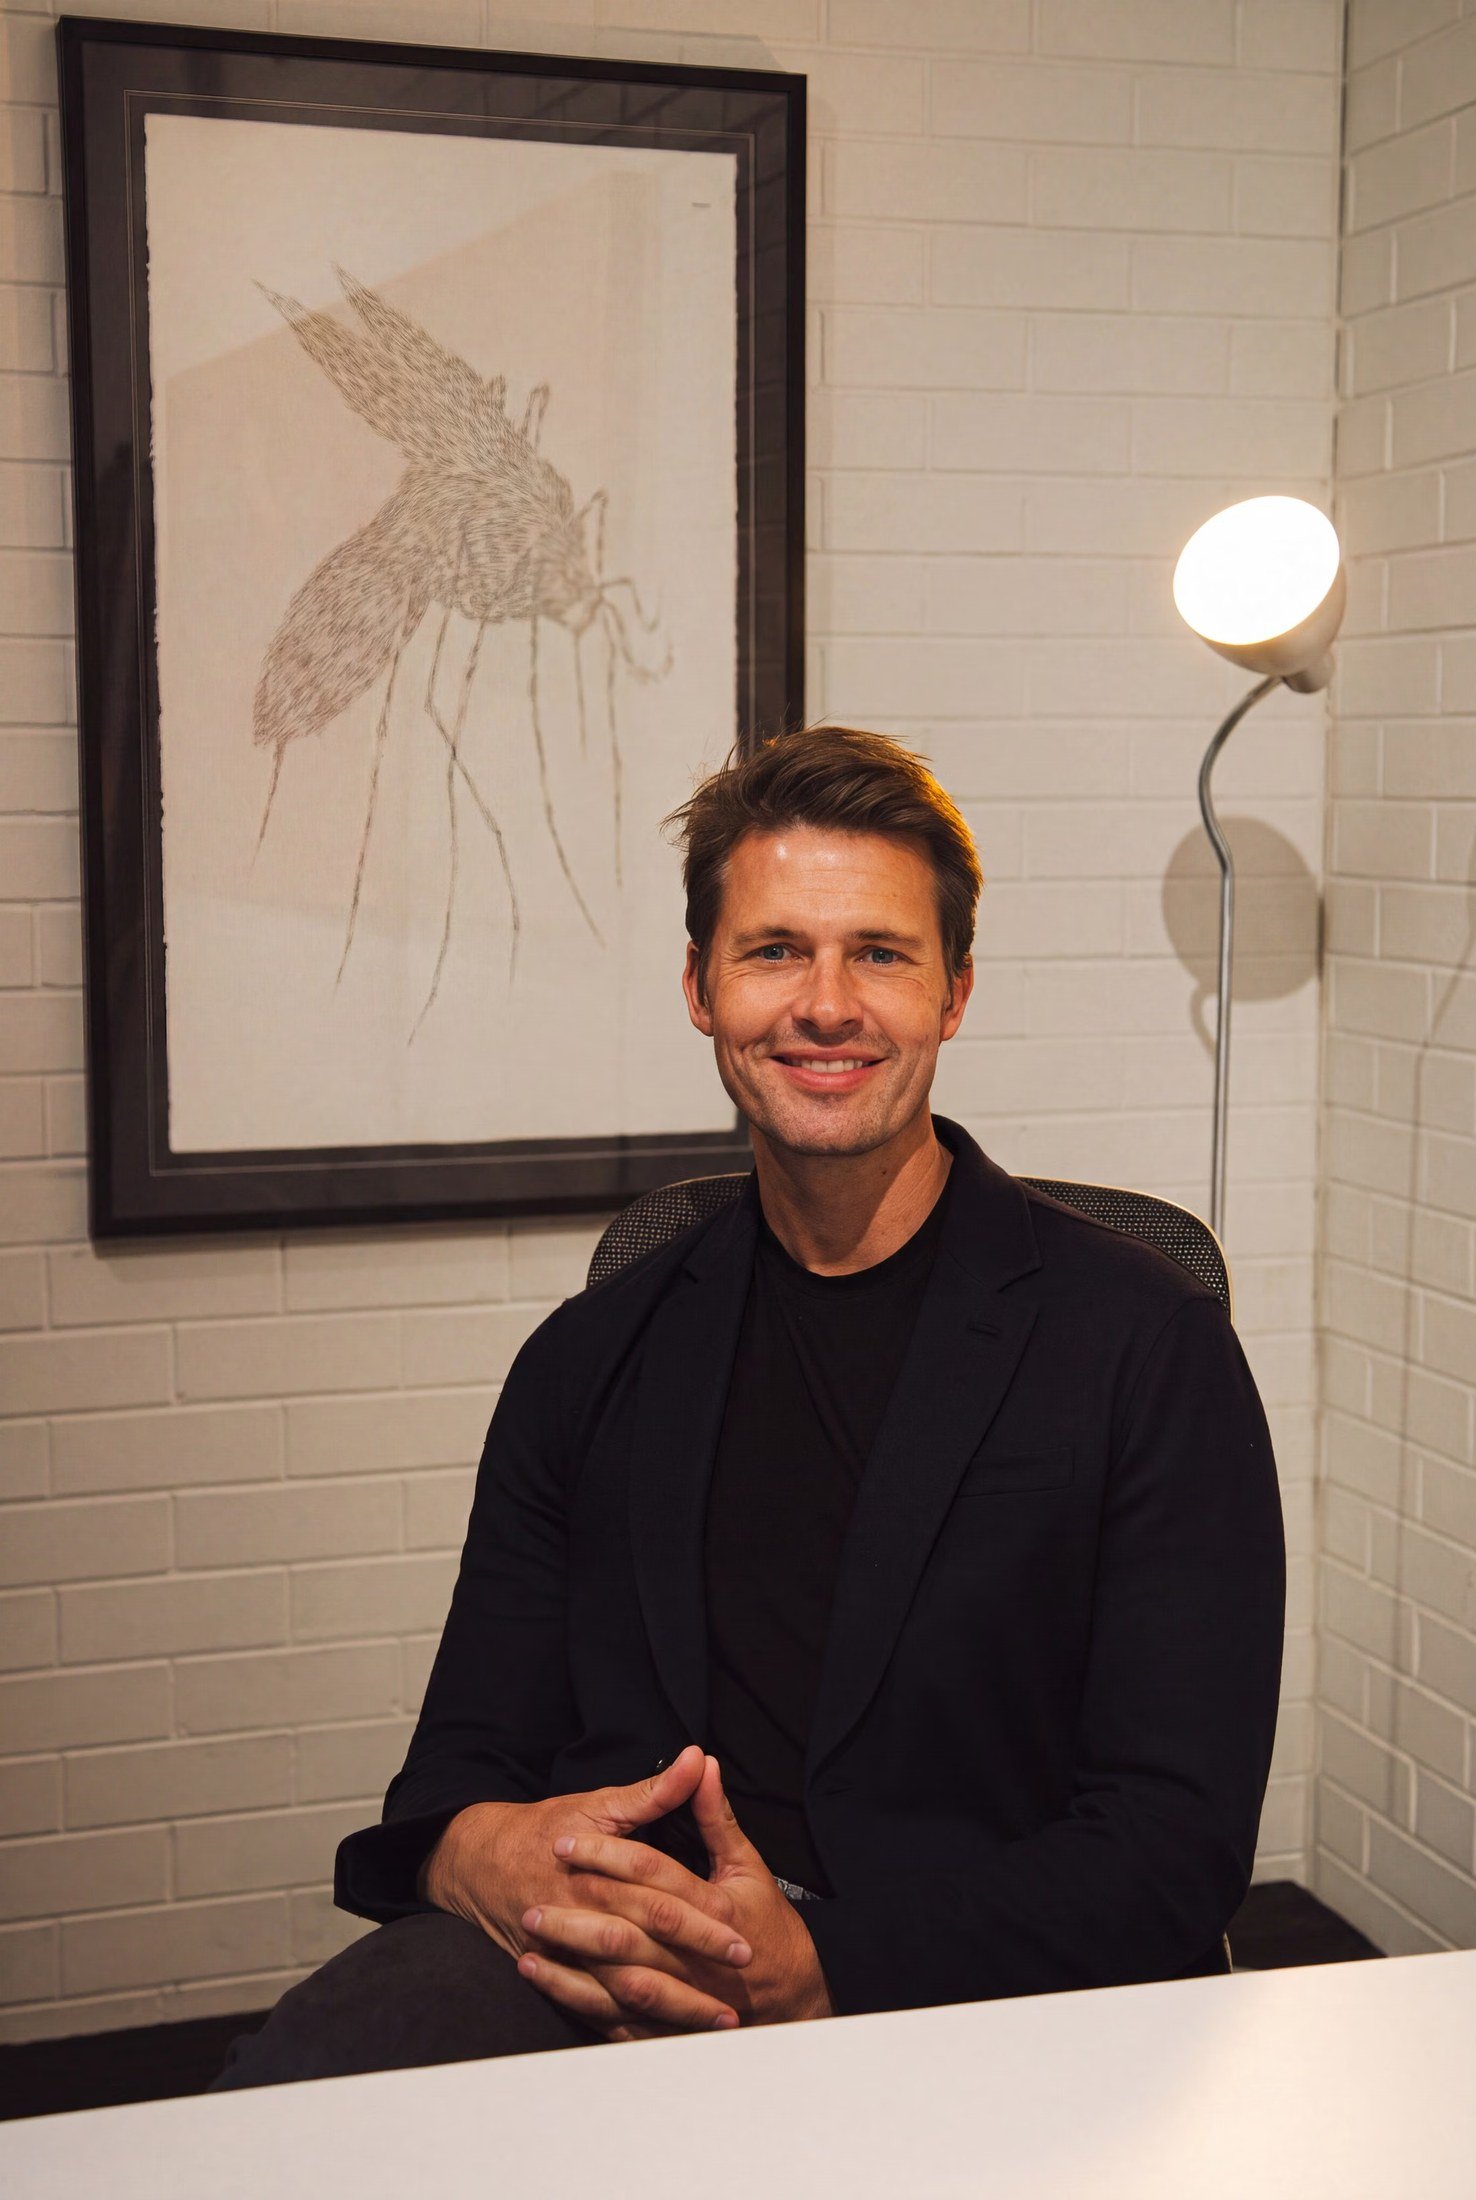
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works with businesses of every size across Australia, and our team works the same way.
Childcare
Liability
PI
Property
Qualifications
FAQs
Approved services must hold public liability cover under the National Regulations, unless a state or territory government indemnity applies.
Yes. Each family day care educator must hold public liability insurance. Home insurance generally excludes business activities.
Not always. Claims about care, supervision or a care plan may fall under professional indemnity instead.
Not automatically. Some specialist policies offer an abuse section, subject to underwriting, limits and exclusions.
They can be, if disclosed and accepted. Tell your broker about regular transport, swimming or higher-risk outings.
Long enough to repair, meet regulatory checks and rebuild enrolments. We help you set the period.
If you employ staff, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on your service type, approved places, premises, property values, excursions, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.