Related work
Industry insurance · Food Trucks and Trailers
Brisbane-based, Australia-wide brokers for food trucks, trailers, coffee vans and market stalls. Tell us what you cook, where you trade and what equipment you carry.
Food truck insurance at a glance
Injury and food claims.
Fitout and cooking gear.
The van, truck or trailer.
Income after damage.
The basics
Food truck insurance combines liability for your customers with cover for your kitchen equipment and income. Your truck, van or trailer is insured on a motor policy alongside it.
Insurers look at what you cook, fryers and gas, where you trade, your equipment values, turnover and claims history.
What you cook and serve.
Fitout, gas and power.
Markets, events and streets.
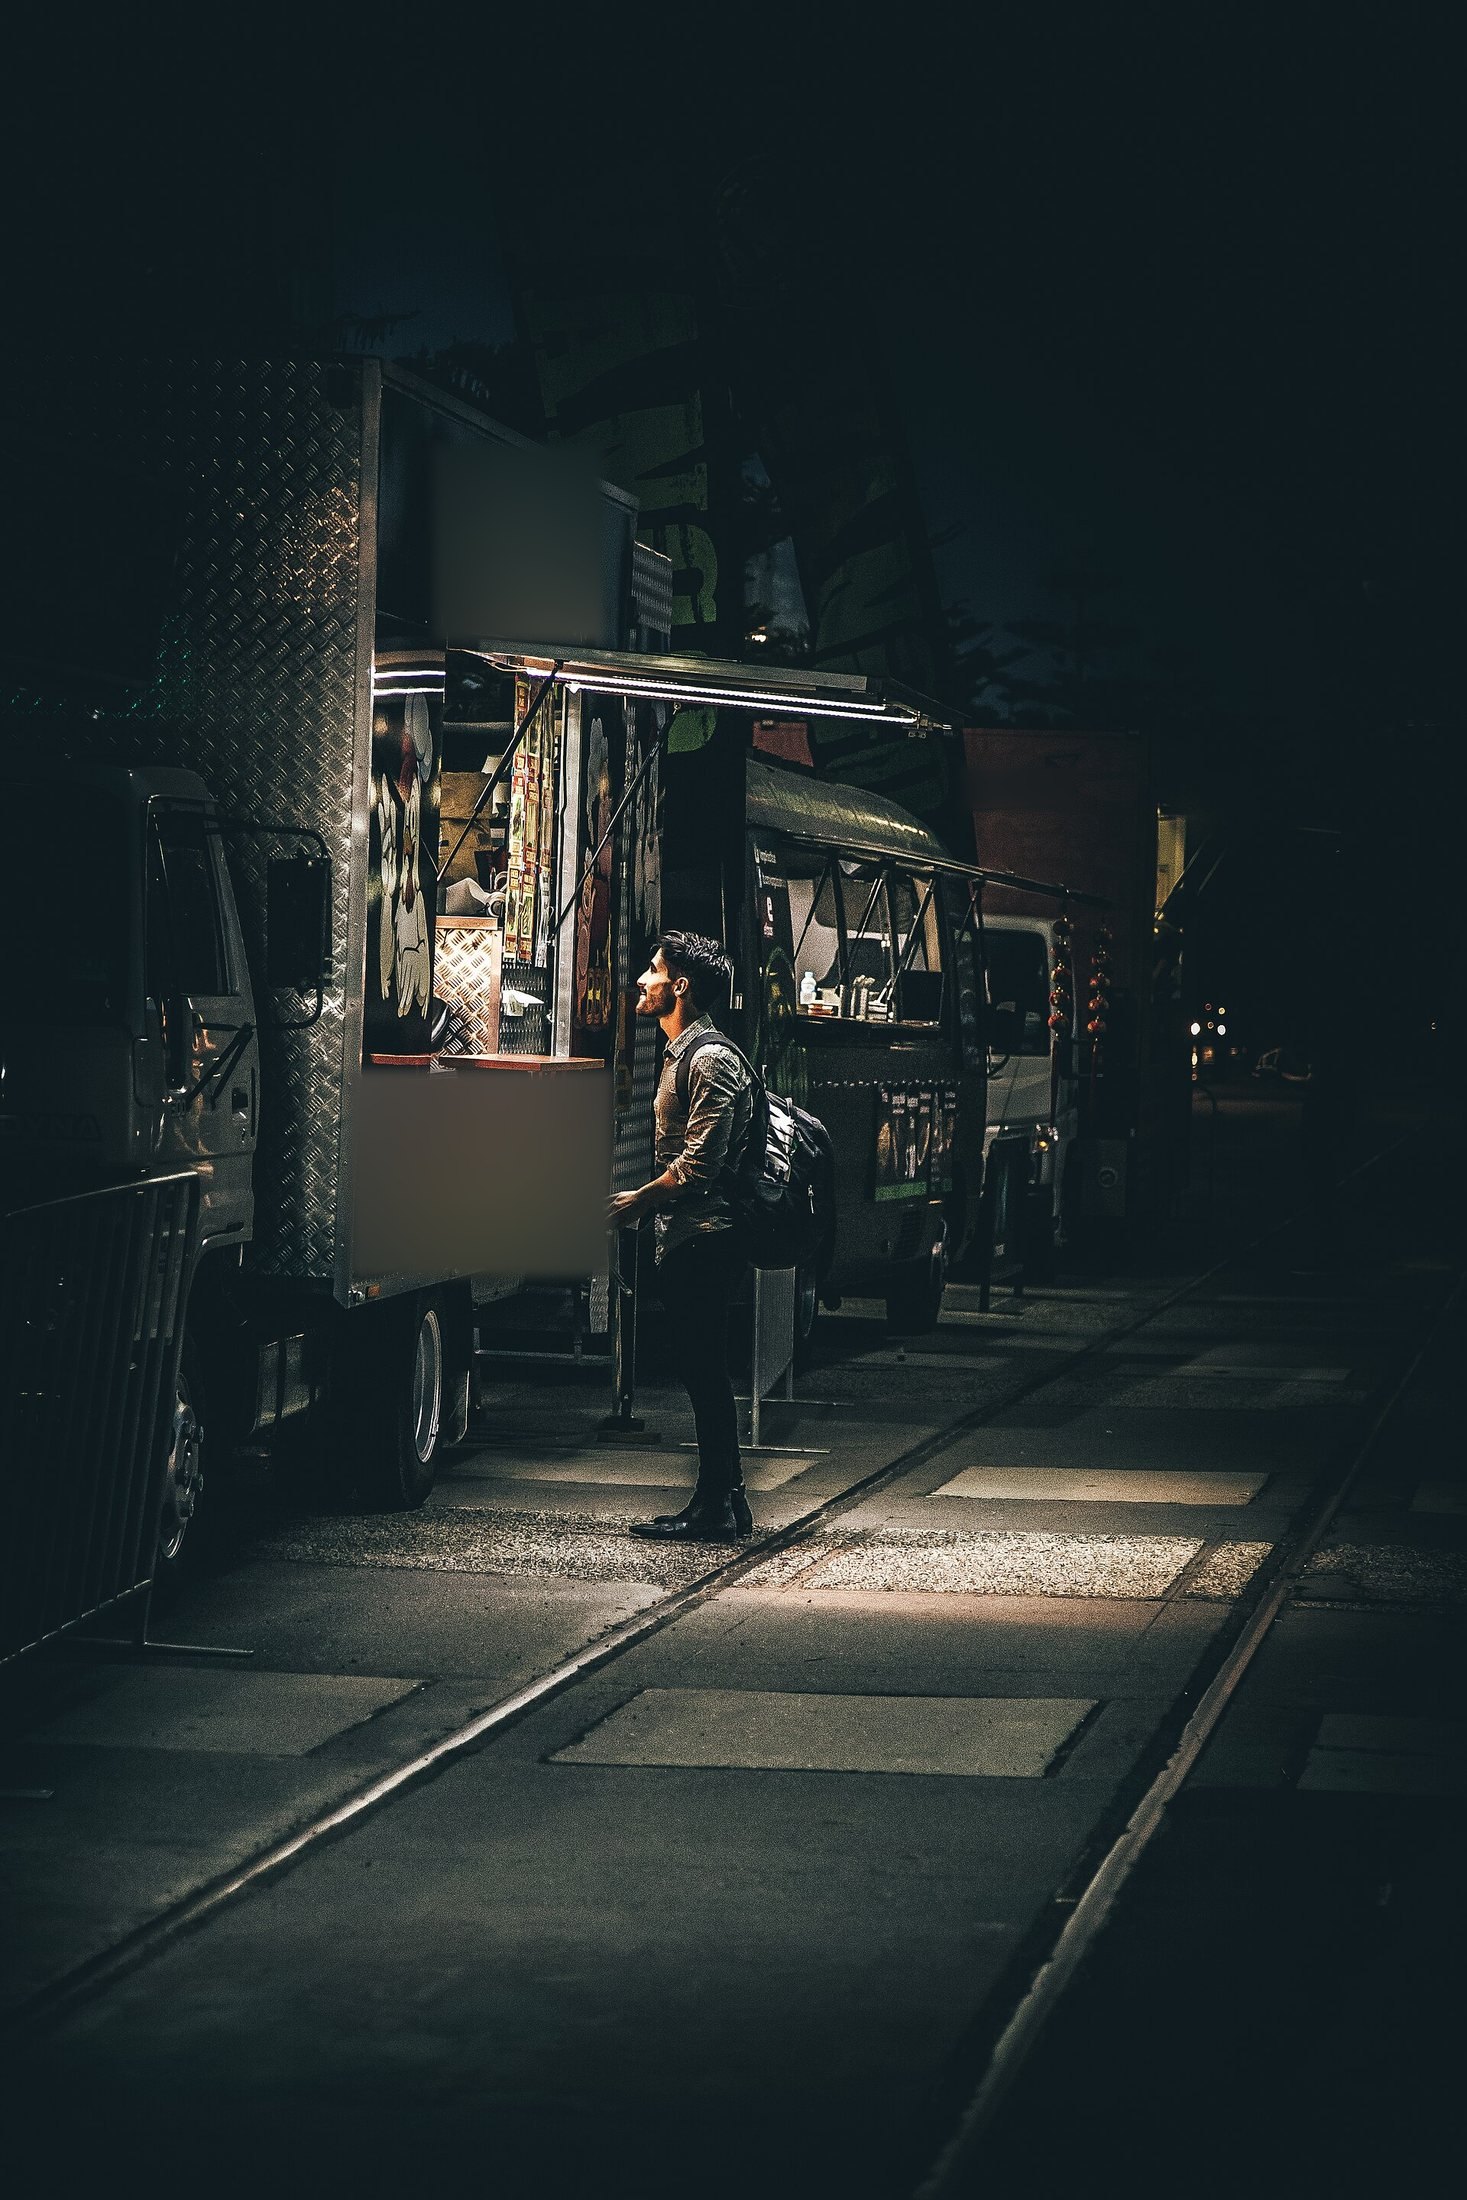
Cover that travels with your kitchen.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Coffee and drinks from a van or trailer. Start with liability and equipment.
Cover options
Most food businesses need a mix, not every policy. Your broker helps you choose what fits.
Customers hurt by spills, burns or a collapsing awning.
Cooking gear, fridges and fitout damaged by fire, theft or storm.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us about your truck.
What we ask
Two food trucks of the same size can be very different risks. These details shape your cover.
01
Menu, fryers and open flame.
02
Gas bottles and generators.
03
Markets, events or streets.
04
Fitout and appliance values.
05
Expected sales this year.
06
Who works the van.
Booked a big festival or a new council site? Check their insurance terms first.
Contract requirements
Councils, events and venues often ask for proof of public liability before you trade. Some name a limit or ask to be named.
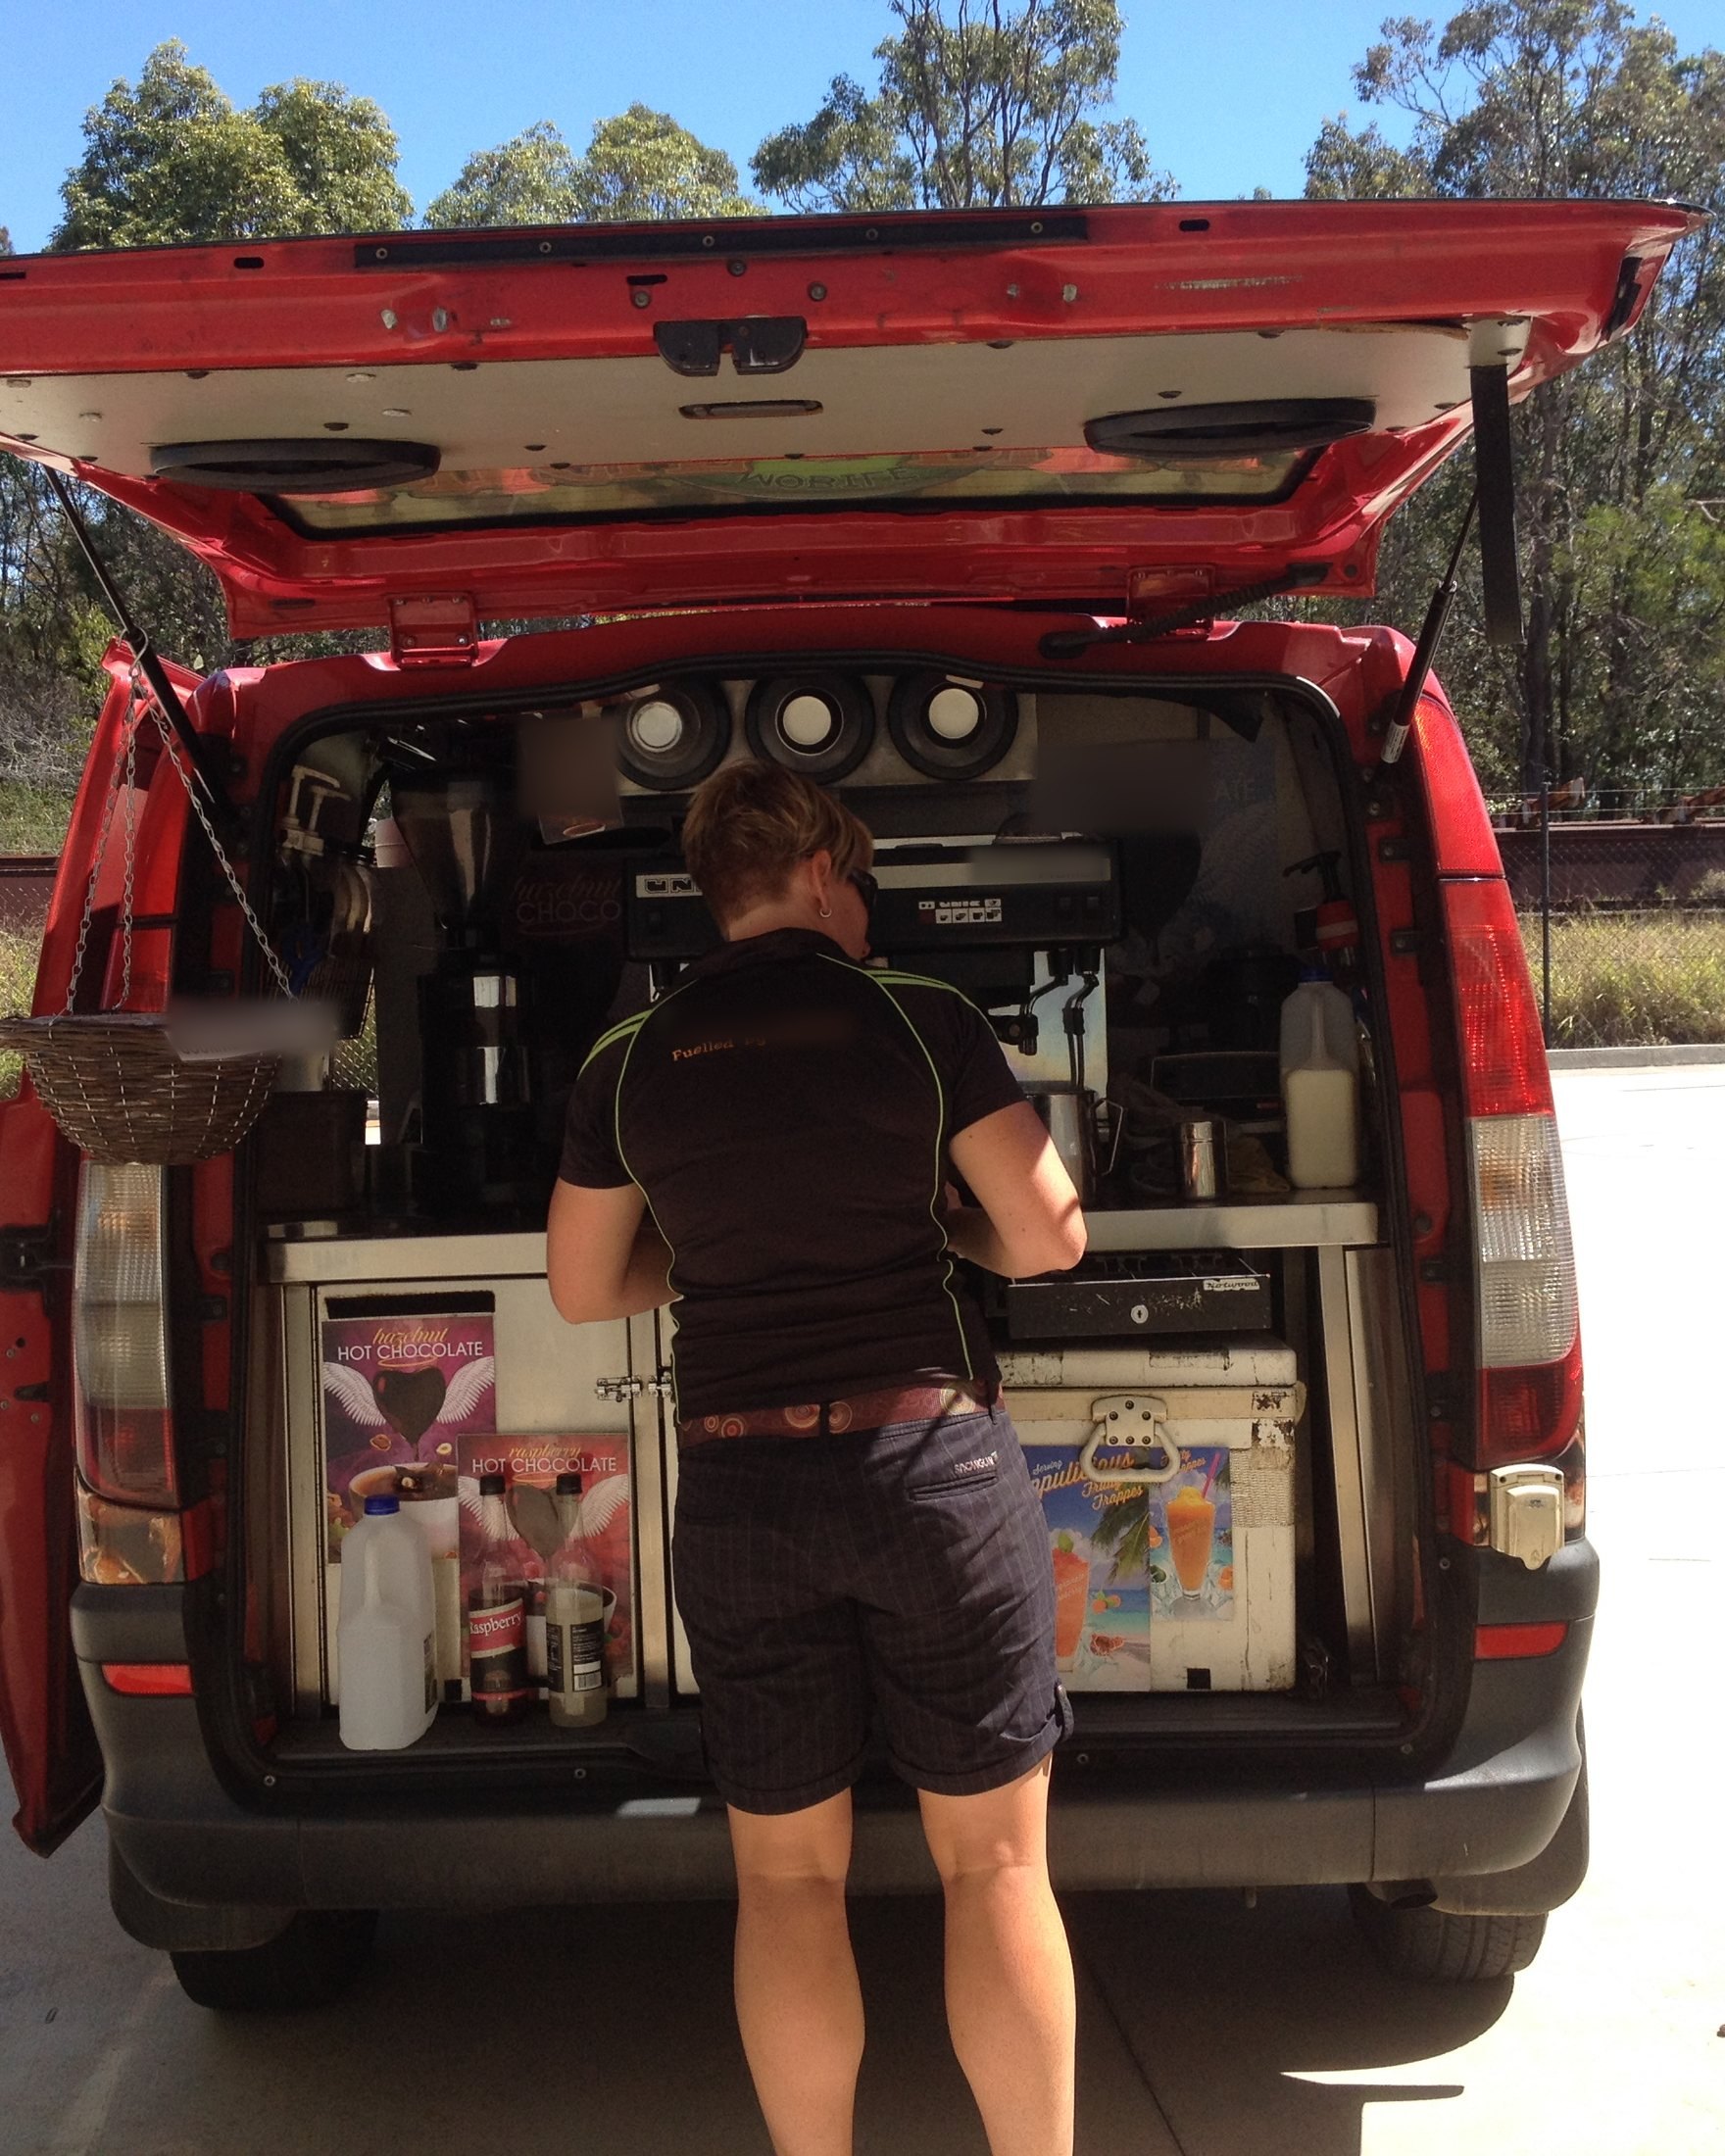
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From business clients
What our clients say, in their own words.
Illustrative example · Food truck
Illustrative example, not a real client. A coffee van operator buys a larger truck with fryers and a grill and starts trading at weekend festivals.
We would check the new cooking is disclosed, equipment and fitout values, breakdown and spoilage, and each festival’s terms.
The new truck and festivals are covered before the first event.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“We are a fast-paced business and rely heavily on Daniel and his team to ensure all our insurance needs are met. Their fast turnaround time is truly second to none, which is crucial for us. We have been using Daniel and his team for multiple years and have always been impressed by their professionalism and efficiency. Highly recommended!”
“Worked with Luke on some niche insurance for our new business and he was fantastic at working through the ambiguity and finding us something that worked! Would recommend to others in the same position, will be referring Luke and the team to others.”
“Highly recommend – very quick, responsive, and so helpful! Saved me from a massive headache and made the whole process simple and easy to understand. Will definitely be using priority insurance brokers again!”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your menu, equipment, vehicle, events and turnover.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works with businesses of every size across Australia, and our team works the same way.
Hospitality
Liability
Equipment
Events
Qualifications
FAQs
One incident, like a fryer fire or a customer slipping on a spill, can be costly. Councils and events often ask for cover too.
Often. Councils, events and private venues commonly ask for proof of public liability before you can trade.
Generally no. Motor cover is for the vehicle. Cooking equipment and fitout need their own cover.
It can be. Machinery breakdown cover can include spoilage as an option.
Yes. We help food trucks, market stalls, pop-ups and semi-permanent food court operators.
Yes. Bundling liability, equipment and vehicle cover makes it easier to manage, with monthly payments available.
If you employ staff, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on what you serve, your equipment values, where you trade, turnover and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
Photo credits: Top photo (cropped and edited) by Kgbo, CC BY-SA 4.0; On-site photo (cropped and edited) by Kgbo, CC BY-SA 4.0; Banner photo (edited) by Kgbo, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.