Related work
Industry insurance · Hotels and Accommodation
Brisbane-based, Australia-wide brokers for hotels, motels, resorts and hostels. Tell us about the property, the rooms, the revenue and everything else that happens on site.
Hotel insurance at a glance
Building, fitout and contents.
Rooms and common areas.
Income after damage.
Lifts, HVAC and refrigeration.
The basics
Hotel insurance is the mix of covers an accommodation business needs. The building, the trading business and guest liability may belong to different parties, so we start with who owns what.
Insurers look at construction, location, rooms, revenue, food and liquor, functions, pools and gyms, plant and claims history.
Rooms, fitout and plant.
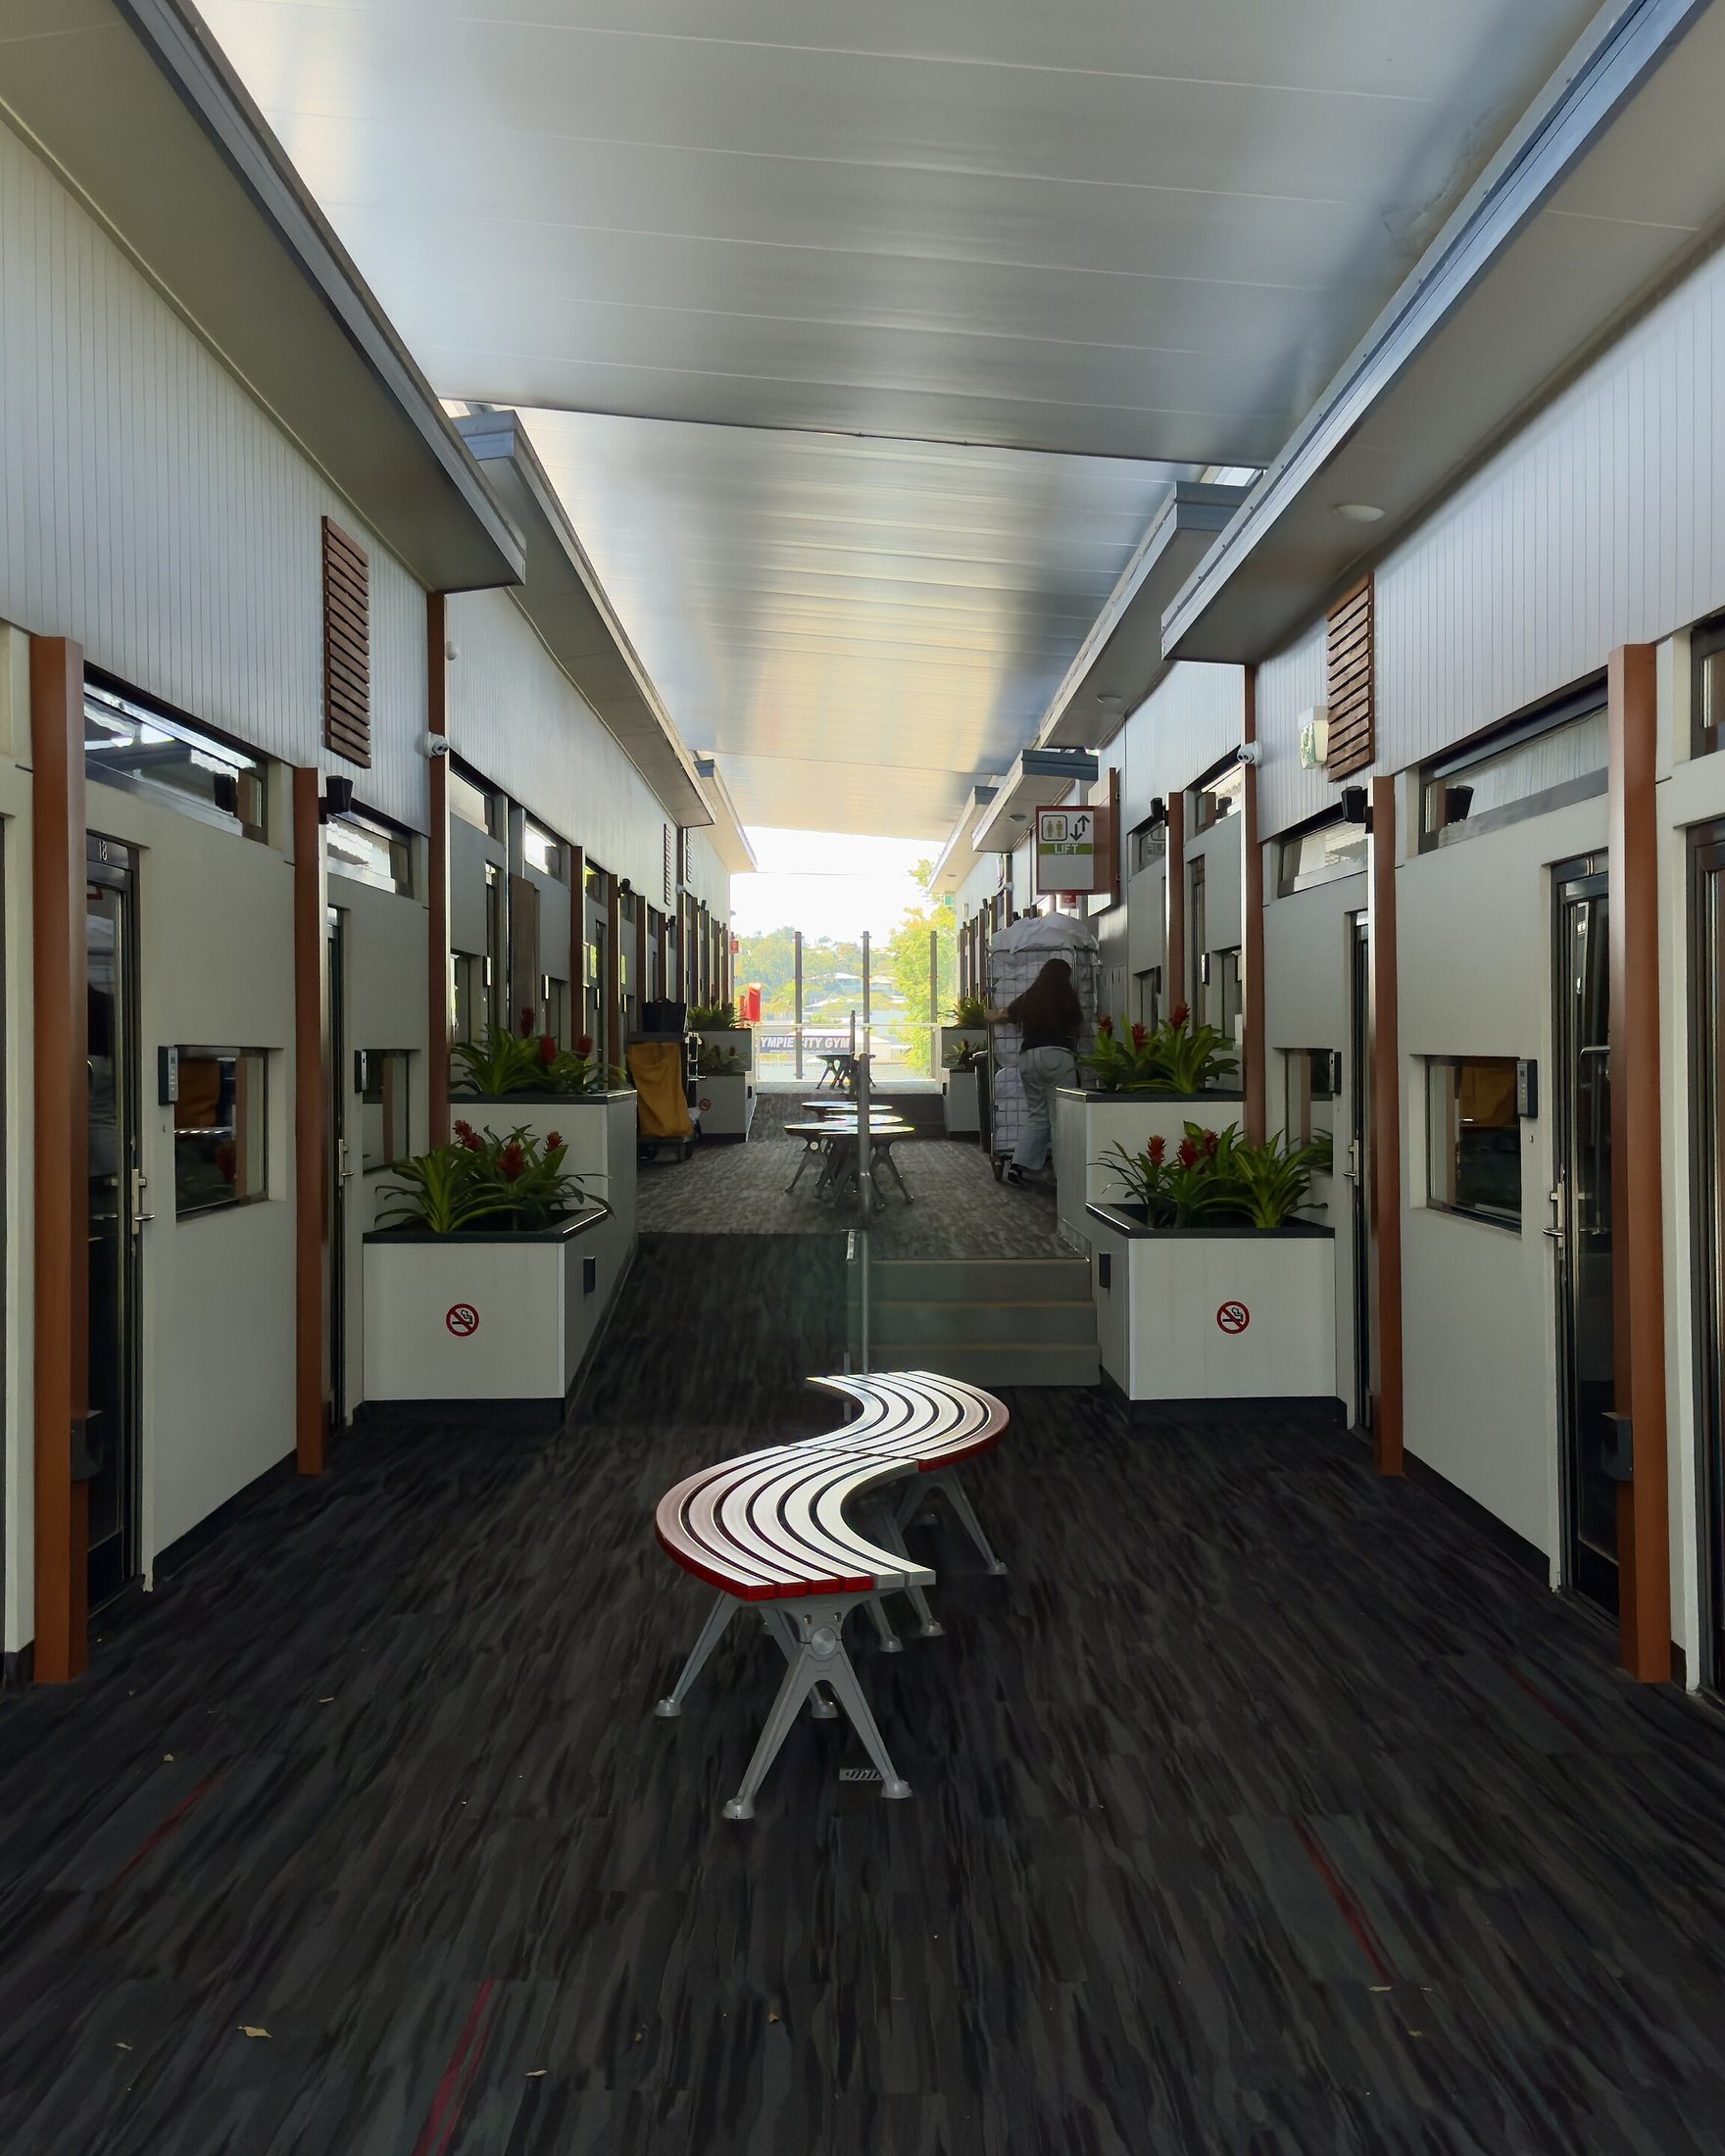
Rooms, pools and common areas.
Revenue, staff and systems.
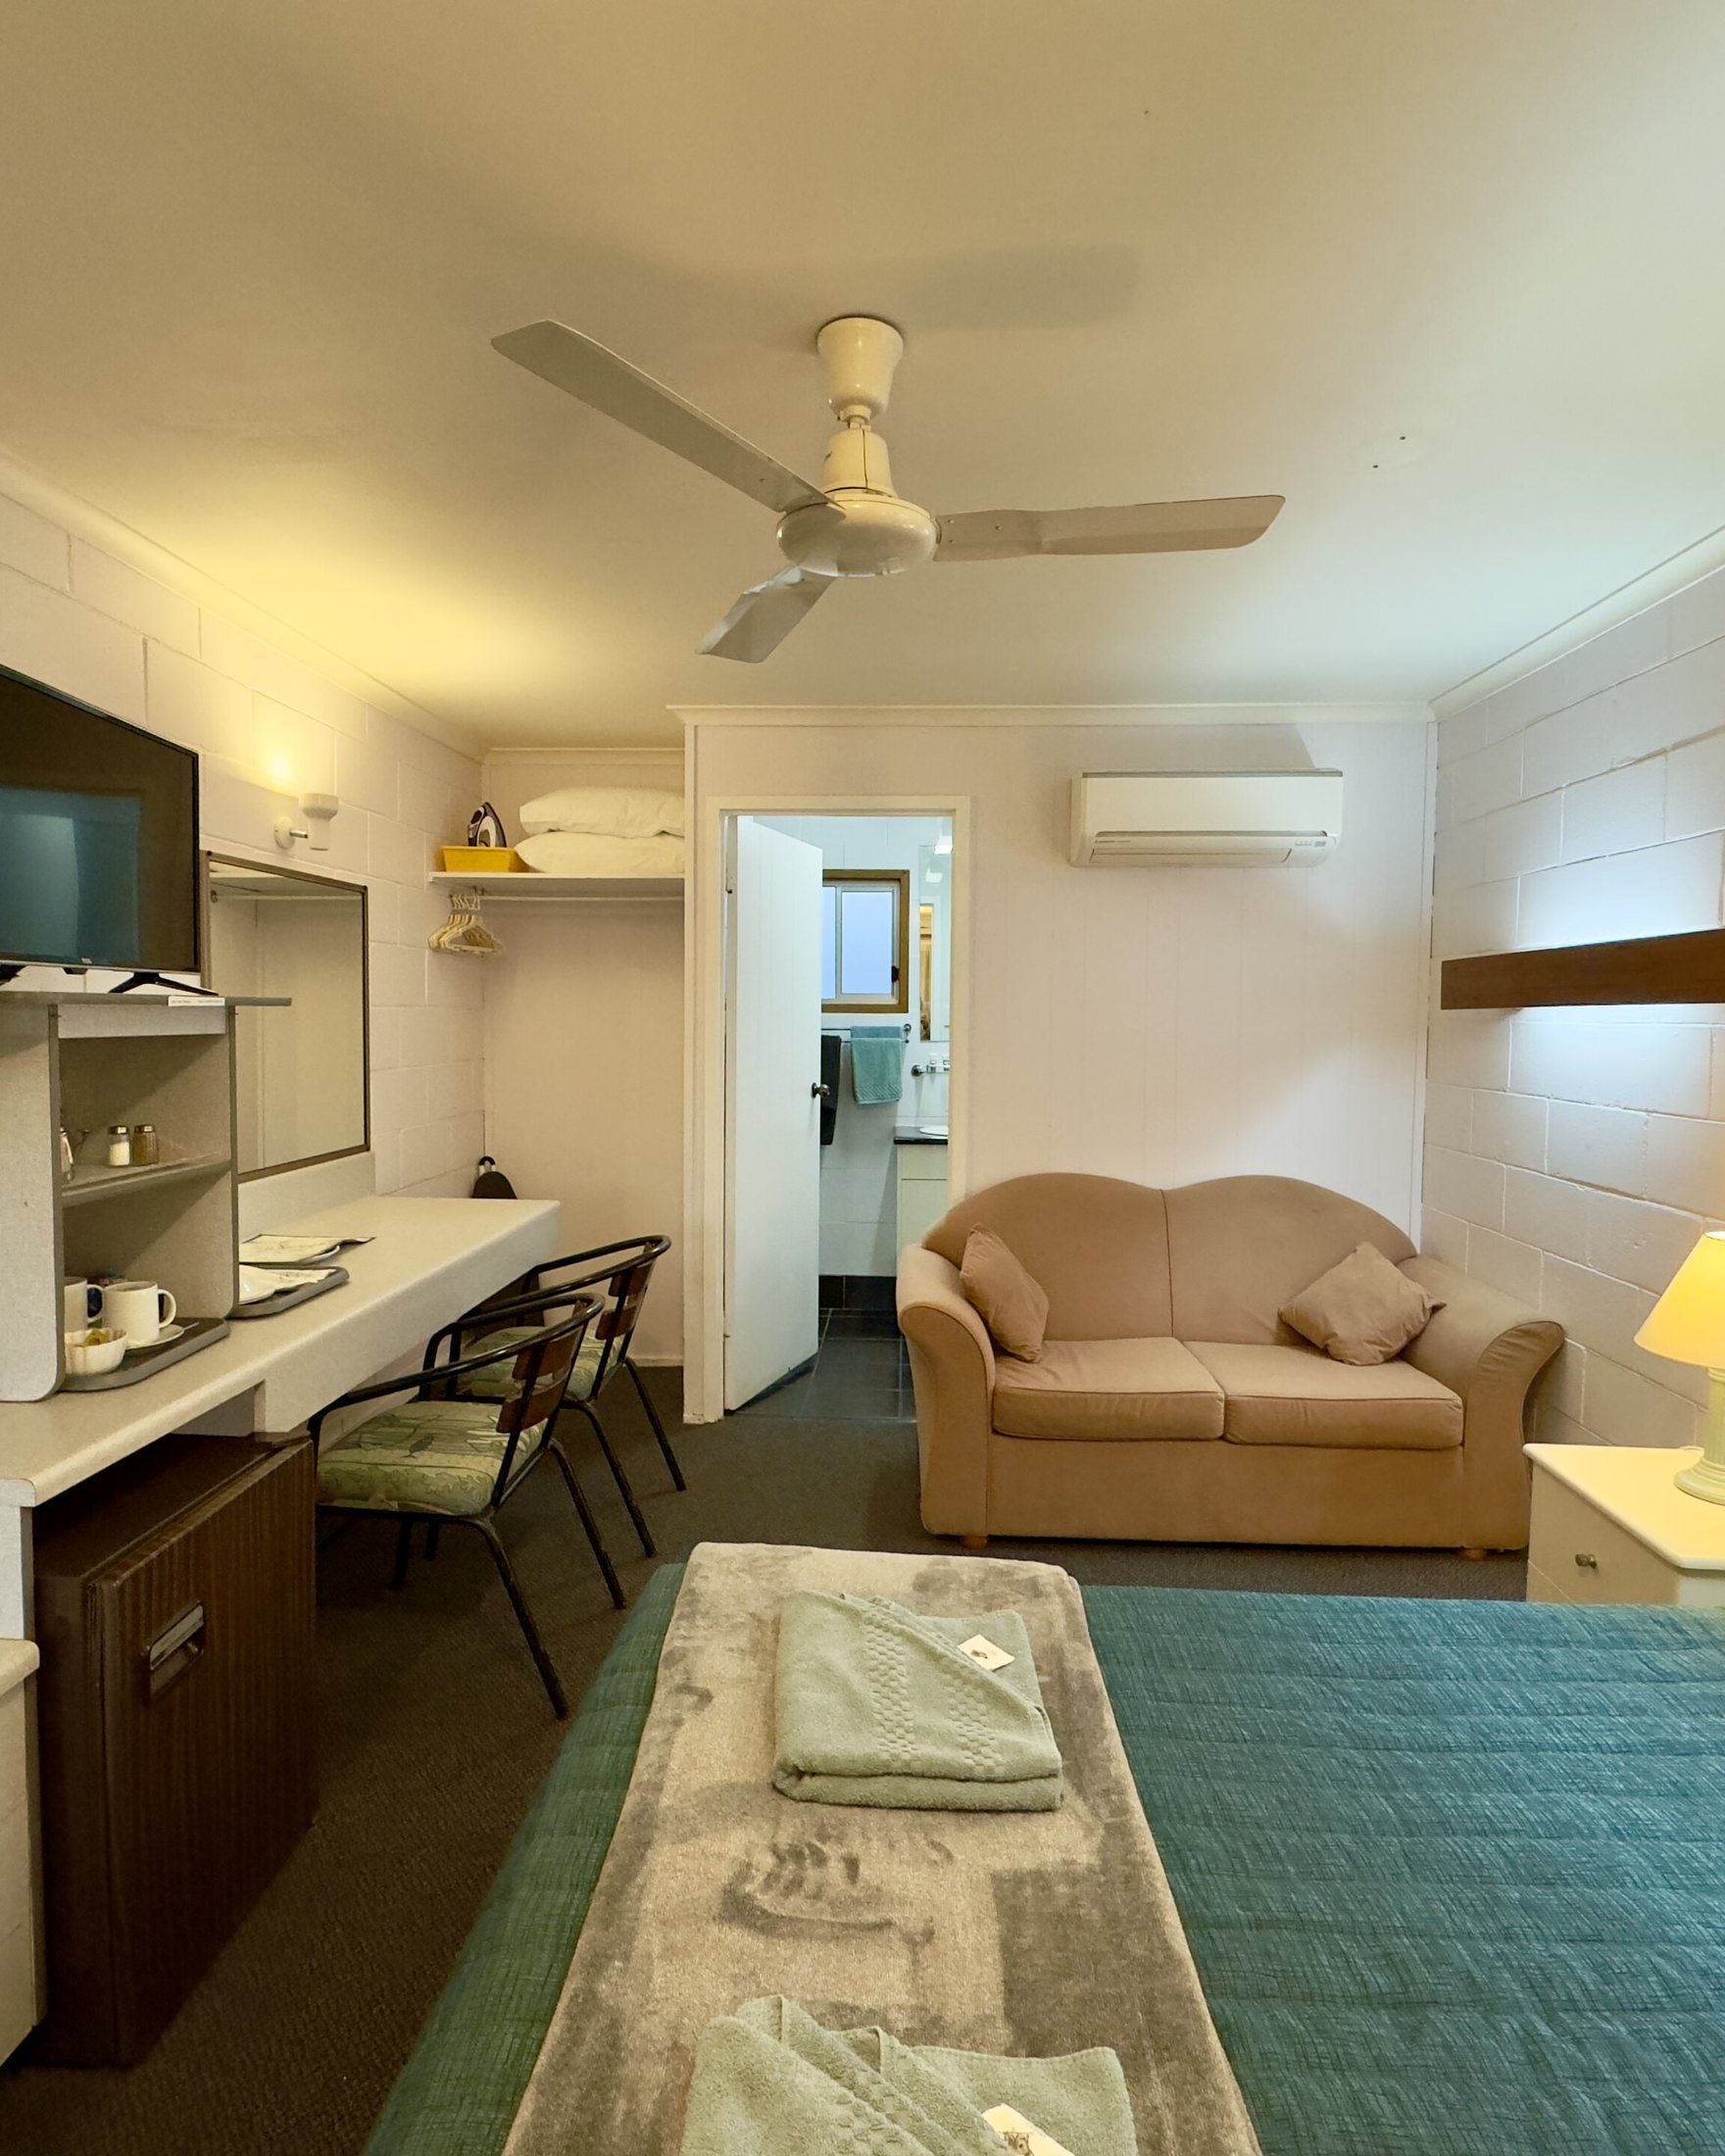
Cover for the hotel you actually run.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Cover options
Most hotels need a mix, not every policy. Your broker helps you choose what fits.
Building, rooms, contents and stock, including larger sites.
Claims from guests or visitors hurt in rooms or common areas.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us about your hotel.
What we ask
Two hotels with the same rooms can be very different risks. These details shape your cover.
01
Building, business and lease.
02
Rooms, food, bars and functions.
03
Pools, gyms and balconies.
04
Materials, age and fire safety.
05
Cyclone, flood and bushfire.
06
Lifts, HVAC and kitchens.
Renovating, adding rooms or starting weddings? Tell your broker before it happens.
Contract requirements
Leases and management agreements often say who insures the building, fitout and business. Check before you sign.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From business clients
What our clients say, in their own words.
Illustrative example · Accommodation
Illustrative example, not a real client. A regional motel turns its breakfast room into a licensed restaurant and starts hosting small functions.
We would check the new food, liquor and function activities are disclosed, products liability, kitchen breakdown and revenue figures.
The restaurant and functions are covered from opening night.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Priority Insurance Brokers made choosing my businesses insurance a breeze. Their team has made me a tailor made package that suits me perfectly. I’d highly recommend them to anyone”
“Daniel has been great to work with. After a lot of stress and expensive quotes got me the best price for my business and very fast too. Thanks”
“Amazing service and makes it so easy for business owners to get the insurance coverage they need. Daniel went above and beyond to get us where we needed to be.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your property, rooms, revenue, facilities, lease and current cover.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works with businesses of every size across Australia, and our team works the same way.
Hospitality
Property
Liability
Revenue
Qualifications
FAQs
There’s no single policy. Most hotels consider property, public and products liability, business interruption, breakdown, cyber and motor cover.
It can, where building cover is arranged and you have an insurable interest. Lessees and owners should confirm who insures it.
Tell us what you own, what the landlord owns and what the lease asks each party to insure.
Yes. Weddings, conferences and events are material activities and should be disclosed.
Yes. Guest facilities change the liability and property risk, so tell your broker about them.
We can review why it was declined and approach other insurers. Cover depends on each insurer’s appetite.
If you employ staff, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on property values, location, construction, revenue, guest facilities, liquor, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
Photo credits: Top photo (edited) by Kgbo, CC BY-SA 4.0; Overview photo (cropped) by Kgbo, CC BY-SA 4.0; On-site photo (cropped) by Chris Olszewski, CC BY-SA 4.0; Banner photo by Kgbo, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.