Related work
Industry insurance · Directional Drilling
Brisbane-based, Australia-wide brokers for horizontal directional drilling contractors. Tell us the bores you pull, the services you work near and the rigs you run, and we’ll help you set up the right covers.
Directional drilling insurance at a glance
Damage to services and property.
HDD plant and support gear.
Gas, power, water and telco.
What principals ask for.
The basics
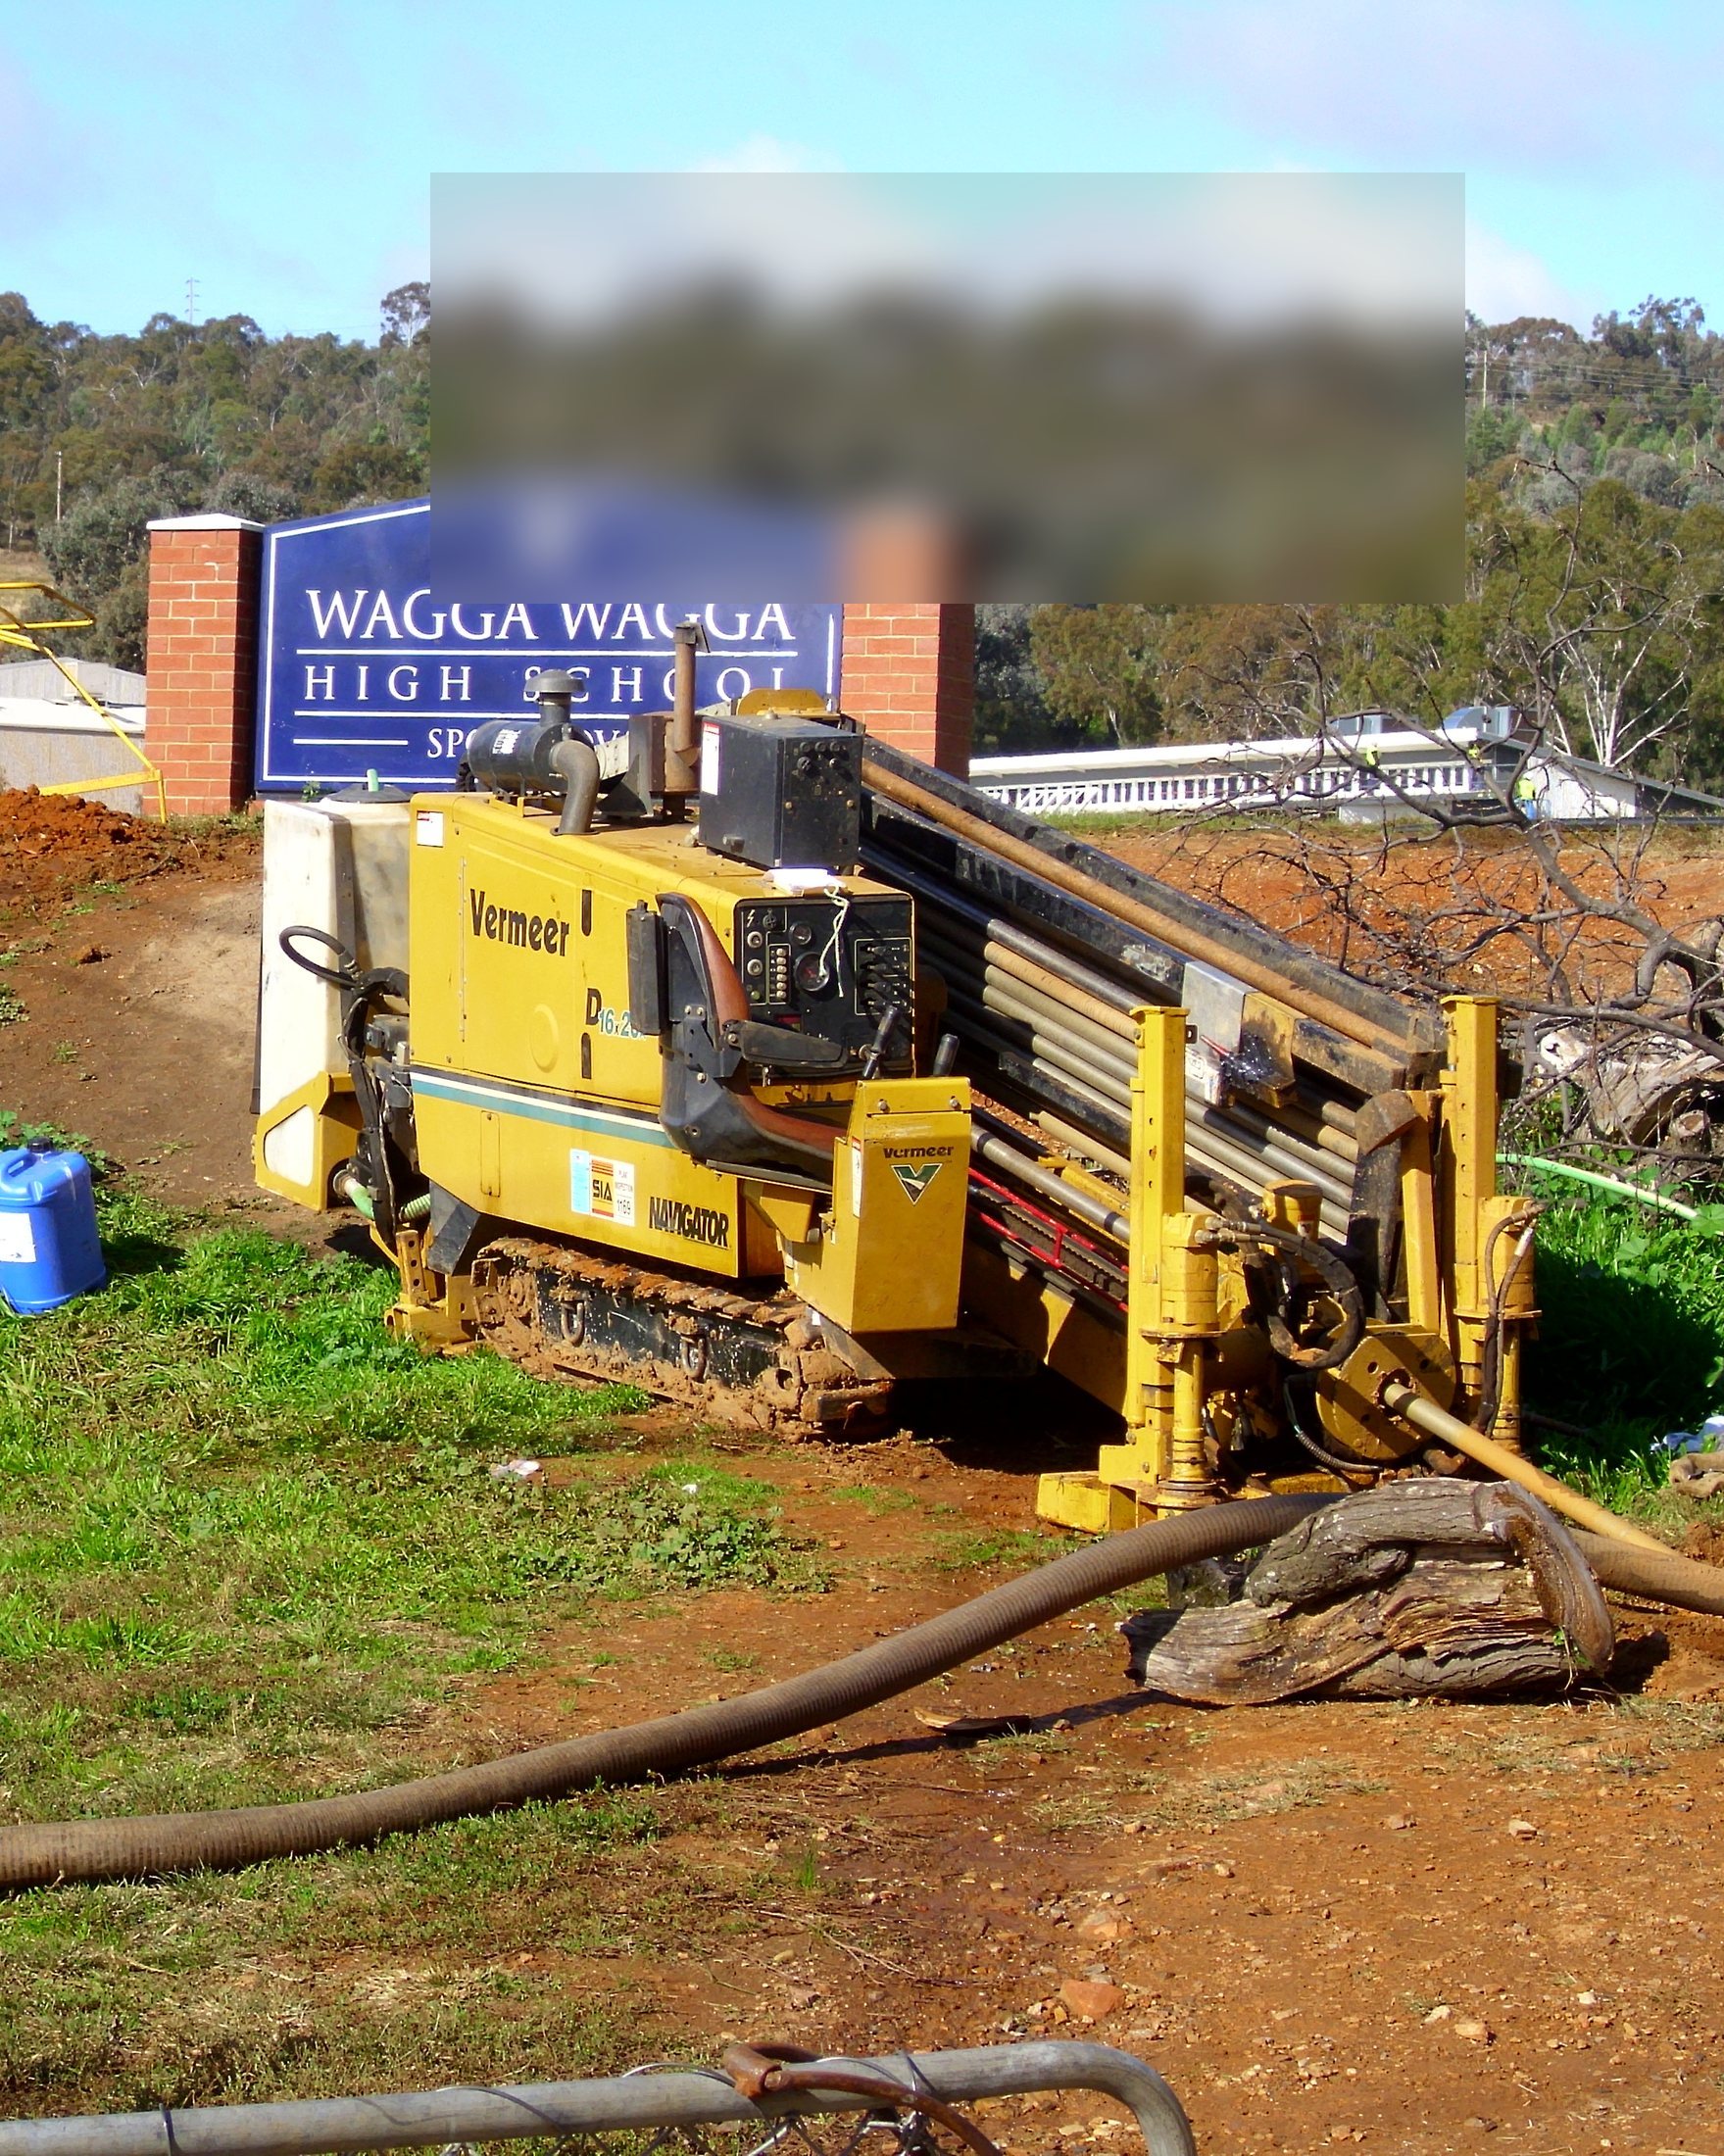
Directional drilling contractors insurance is the mix of covers an HDD or trenchless install business needs. Crossing roads, rivers and services sits outside many standard excavation policies.
Insurers look at bore length and diameter, product being installed, nearby services, and how you locate and protect underground assets.
Services, roads and property.
HDD rigs and mud systems.
How you locate services.
Cover that matches how you bore.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Local service installs and crossings. Start with liability and plant.
Cover options
Most HDD businesses need a mix, not every policy. Your broker helps you choose what fits.
Claims from damaged underground services, roads or neighbouring property.
Indemnities, waivers and principal clauses in your contracts.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us how you bore.
What we ask
Two directional drilling businesses of the same size can be very different risks. These details shape your cover.
01
Utility installs, crossings, fibre, water, gas or power.
02
Usual and maximum length and diameter.
03
How congested the corridor is.
04
HDD rigs, mud systems and trucks.
05
Employees or subcontractors.
06
Councils, utilities or builders.
Taking on rail or major road crossings? Tell your broker before you bid.
Site and contract requirements
Utilities and councils usually ask for proof of cover before you bore. Service-location process often sits in the site rules.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From construction clients
What our clients say, in their own words.
Illustrative example · Directional drilling
Illustrative example, not a real client. An HDD crew that usually installs local fibre is offered a dual-carriageway crossing for a water main.
We would check that road crossings and the bore size are declared, the Public Liability limit the utility asks for, and how underground services are located.
The crossing is declared before the first bore.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Efficient and timely. Insurance requirement for a niche business. All members of Priority Insurance Brokers were great to deal with and insurance premium was very competitive. Special thanks to Daniel”
“Daniel and the Priority Insurance team are fantastic to deal with and extremely knowledgable”
“Easy to deal with. Promptly sent me through an insurance proposal for my new business within a day.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your bores.
01
Your bore types, sizes, services, plant, crews and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with civil, construction and other blue-collar businesses, and our team works the same way.
HDD
Civil
Plant
Liability
Qualifications
FAQs
Most need Public Liability sized for underground service risk, plus plant cover for HDD rigs and support gear.
Crossings and congested service corridors change the risk, so fewer standard policies fit without the right description.
Before excavation starts, Safe Work Australia says you must get information on underground services, for example through Before You Dig Australia.
Yes. If the occupation on your policy doesn’t match the work you do, the policy may not respond to a claim. Describe the whole scope.
Yes. Insurers ask about subcontractors because they change your cover and premium. Some policies exclude claims from uninsured or undeclared subcontractors.
It can sit under Public Liability or need environmental liability, depending on the wording. Tell your broker how you manage fluid.
Before you start trading on your own. Work you do through your own business isn’t covered by an employer’s policy.
It depends on your bore types, sizes, services, plant, crew, turnover, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you bore and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
Photo credits: Top photo by GordonJ86, CC BY-SA 4.0; Overview photo (cropped) by Bidgee, CC BY-SA 3.0 au; On-site photo (cropped) by PtrQs, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.