Industry insurance · Photography and Videography
Brisbane-based, Australia-wide brokers for photographers and videographers — weddings, real estate, commercial and content creators. Tell us how you shoot and what gear you carry.
Photographer and videographer insurance at a glance
Injury and venue damage.
Cameras, lenses and drones.
Disputes about deliverables.
Gear away from the studio.
The basics
Standard business insurance may miss the way you work on location, with members of the public, or with high-value cameras, lenses and drones.
Insurers look at wedding and event work, commercial and real estate shoots, studio versus location, travel, hired-in gear and whether you deliver edited content under contract.
Weddings, commercial or content.
Owned, hired and drones.
Venues, brands and agencies.
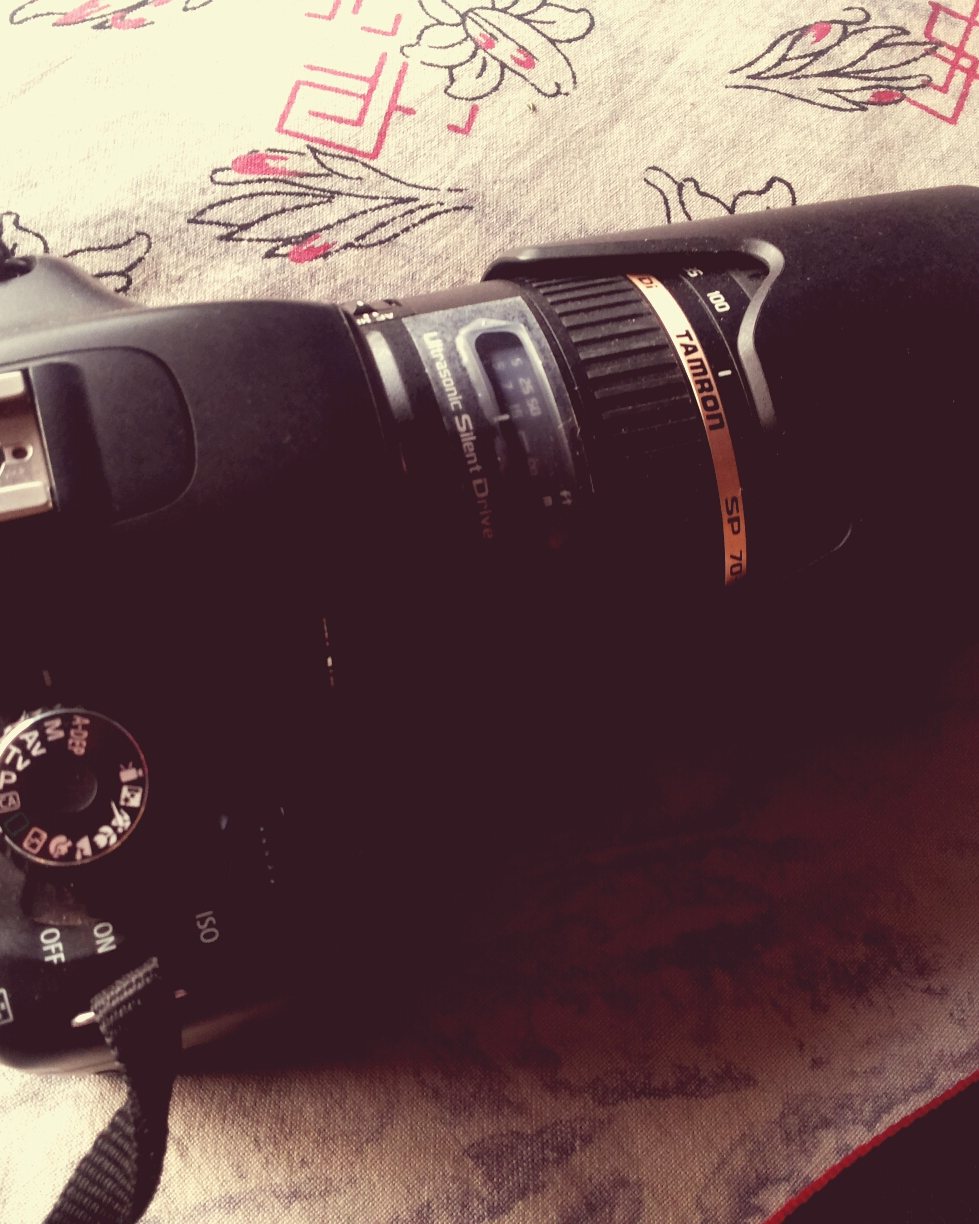
Cover that travels with the kit.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
On-location shoots with guests and venues. Start with liability and gear.
Cover options
Most creative businesses need a mix, not every policy. Your broker helps you choose what fits.
Injury to others or damage to a venue while you shoot.
Claims that your work caused a financial loss or missed the agreed scope.
Risks of running a company, and cyber incidents that stop work.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us how you shoot.
What we ask
Two creatives with the same kit can be very different risks. These details shape your cover.
01
Weddings, commercial, real estate or content.
02
Venues, outdoors and public places.
03
Owned values and hired-in kit.
04
Aerial work and licences.
05
Interstate or overseas shoots.
06
Expected sales this year.
Adding drone work or overseas shoots? Tell your broker before you book them.
Contract requirements
Venues and producers often ask for proof of cover. The brief may name limits and who is responsible for hired gear.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From business clients
What our clients say, in their own words.
Illustrative example · Photography
Illustrative example, not a real client. A wedding photographer books an interstate destination shoot and hires specialty lenses for the weekend.
We would check travel and hired equipment cover, venue liability requirements and that gear sums insured match the kit list.
The shoot and hired lenses are covered before departure.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Daniel and his team were fantastic. They responded quickly, truly listened to our needs, and always acted in our best interest.”
“Priority are always proactive with all our policies, always getting the best price. Love their work.”
“Easy to deal with. Promptly sent me through an insurance proposal for my new business within a day.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your shoot mix, gear values, travel, turnover and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
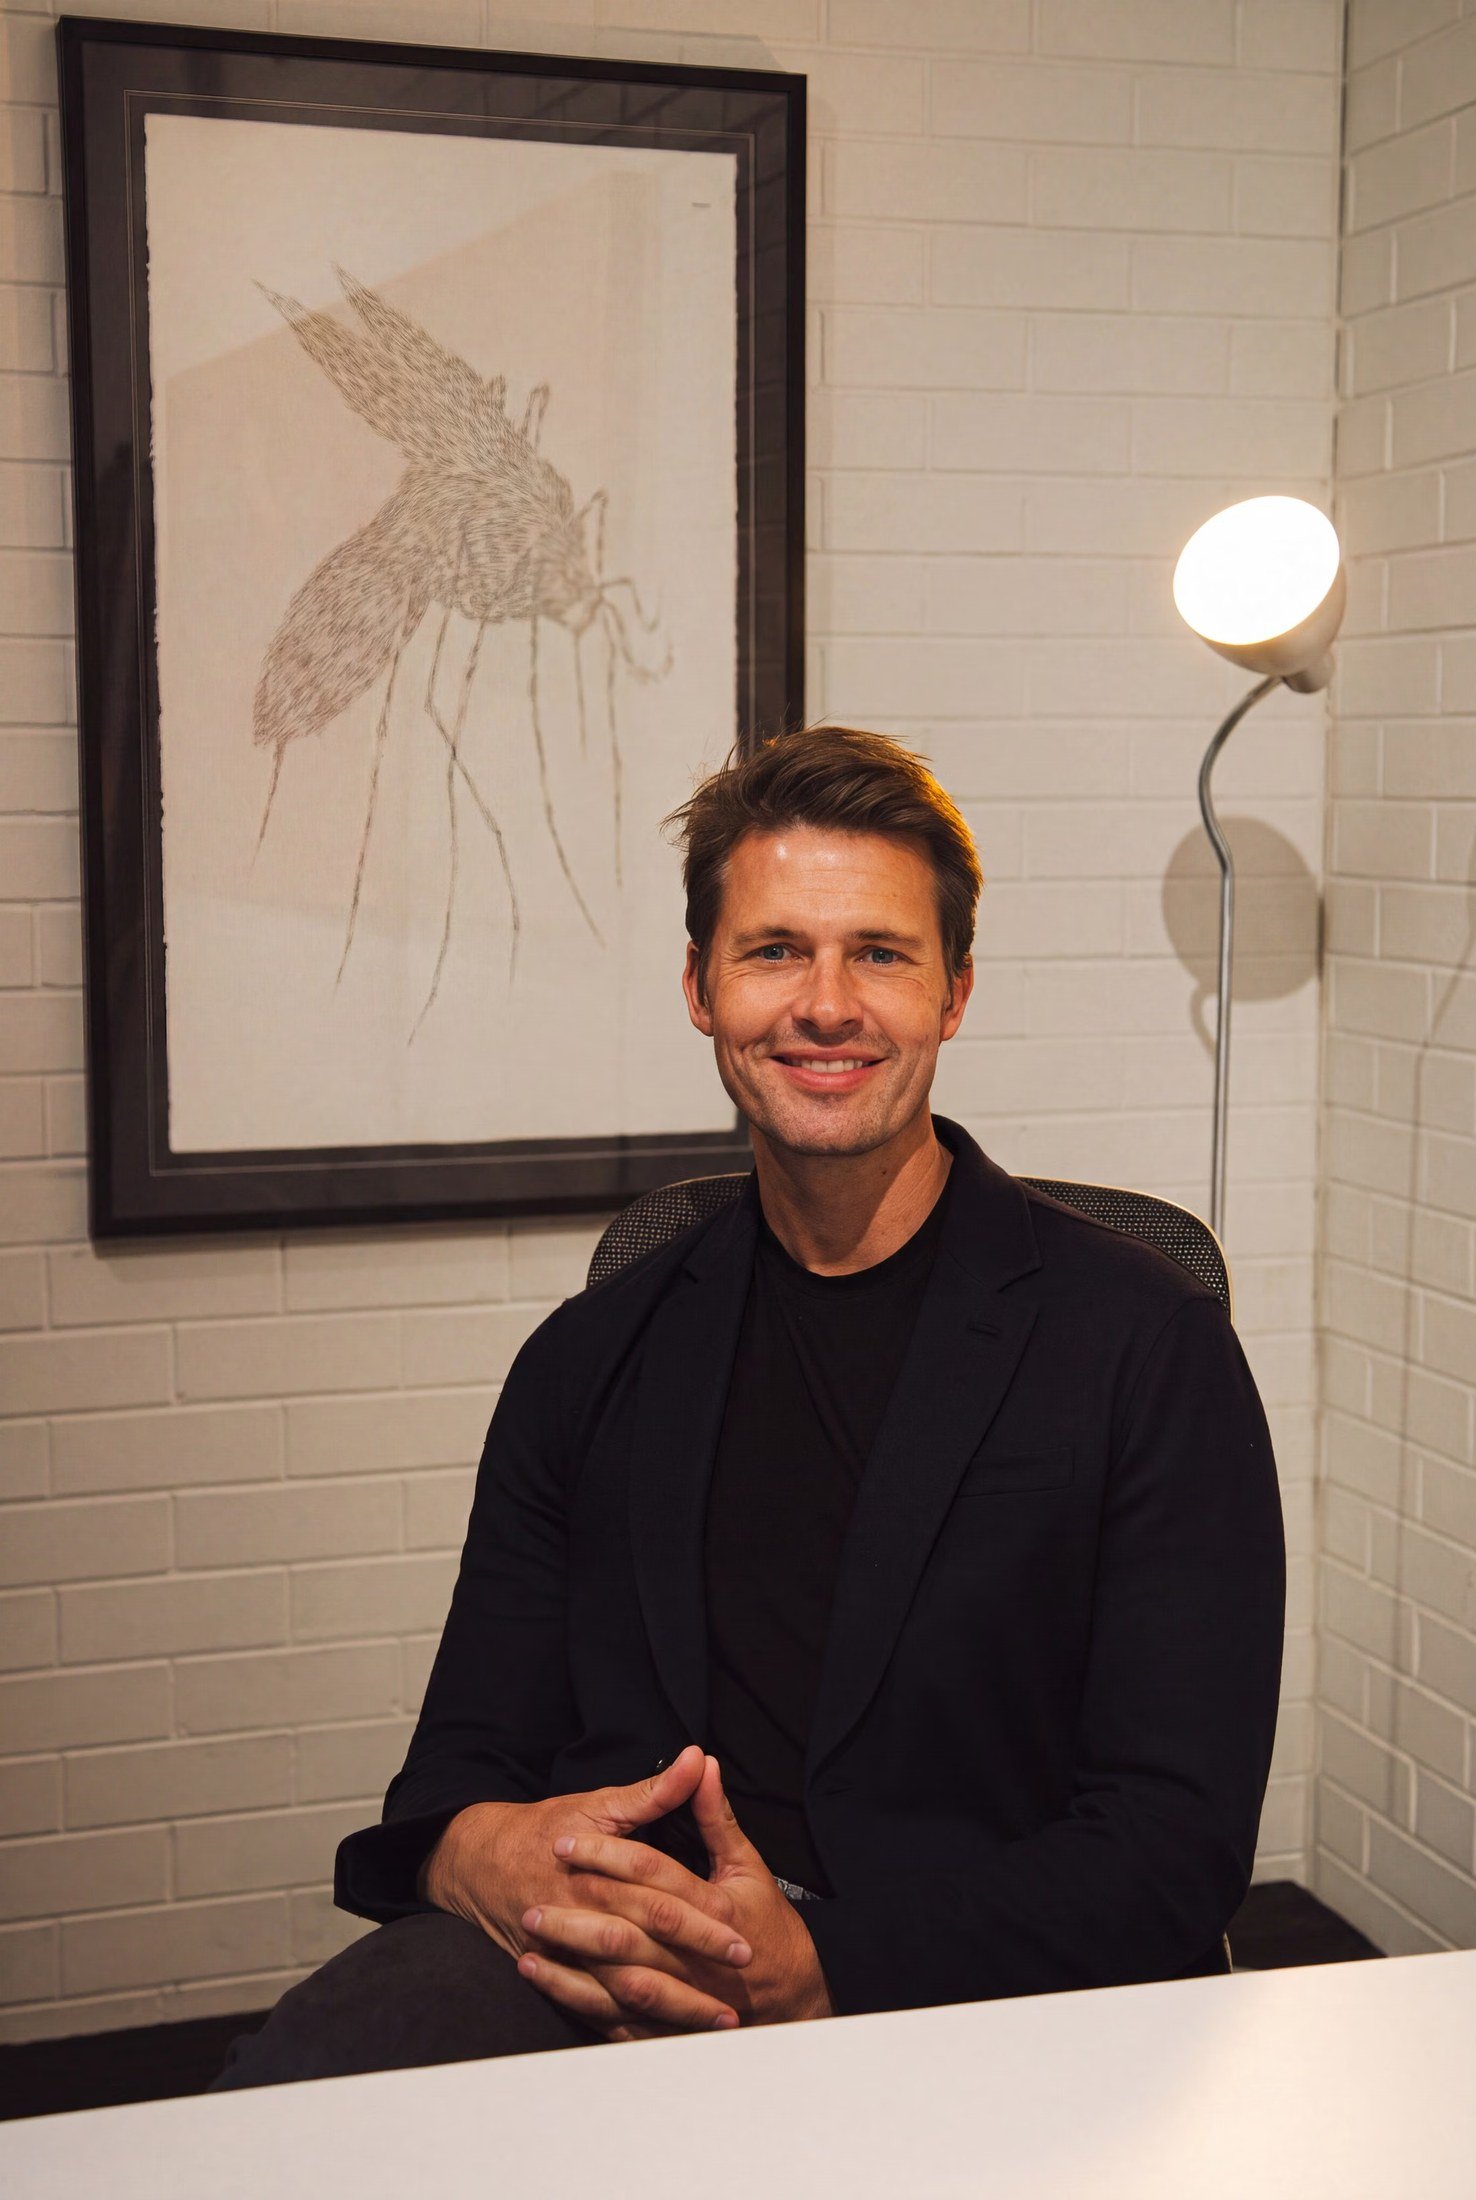
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works with businesses of every size across Australia, and our team works the same way.
Photo and video
Liability
Gear
PI
Qualifications
FAQs
Yes if you work on location, at events or have clients at a studio. Venues and commercial contracts often require it.
Often yes, including worldwide cover for cameras and accessories when disclosed. Tell us where and how often you travel.
Yes. We can arrange cover for the hire period so borrowed kit is protected.
When you deliver services or finished work under contract — albums, brand content, real estate video — and a client could claim financial loss.
They need to be disclosed. Licensing and how you fly them matter to the insurer.
Your work mix, gear list and values, turnover, travel and any venue requirements.
If you employ staff, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on your work mix, gear values, travel, turnover, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
Photo credits: Top photo by Fvvdge, CC BY-SA 4.0; Overview photo (cropped) by TargetAimShoot, CC BY-SA 3.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.