Related trades
Industry insurance · Boilermakers and Welders
Brisbane-based, Australia-wide brokers for boilermakers, welders and fabricators. Tell us whether you work in a workshop, on site or on shutdowns, and we’ll help you set up the right covers.
Boilermakers insurance at a glance
Injury or damage from welding and fabrication.
Welders, grinders and workshop gear.
Sparks, heat and site conditions.
What principals ask you to hold.
The basics
Boilermakers insurance is the mix of covers a welding or fabrication business needs. It depends on whether you work in a workshop, on construction sites, on mobile jobs or on industrial shutdowns.
Hot works, work at height and mine or shutdown sites are often excluded or restricted unless they are declared, so the details of your work matter.
Claims linked to sparks, heat or site work.
Tools, plant and the ute or trailer.
Limits and hot-works conditions.
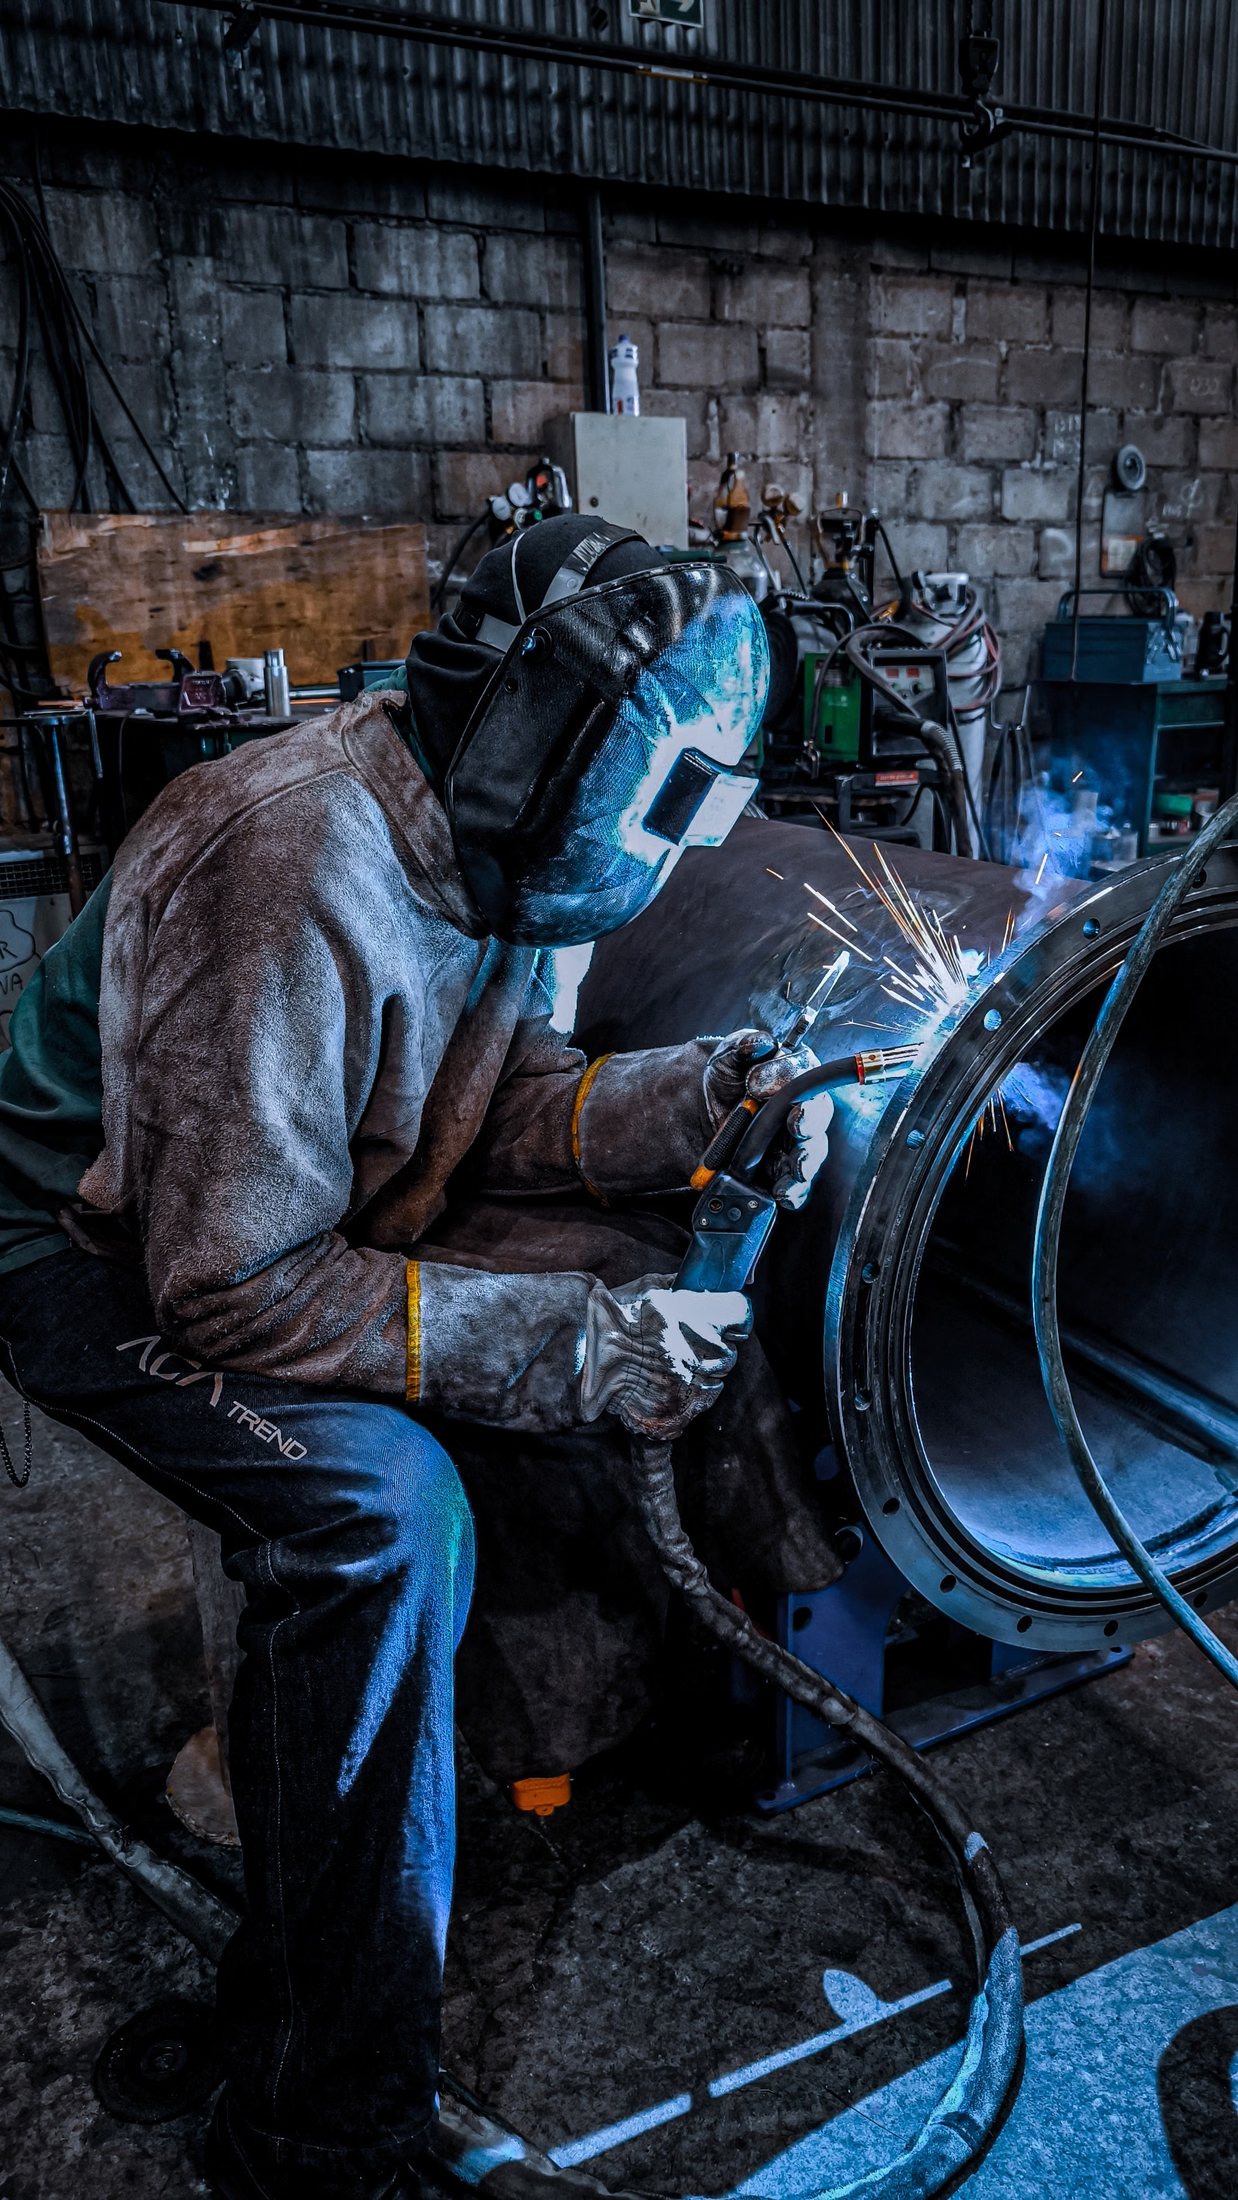
Cover that matches how you weld.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Mine, industrial or high-limit contracts that need careful placement.
Cover options
Most boilermakers need a mix, not every policy. Your broker helps you choose what fits.
Claims that your work injured someone or damaged property, including from hot works.
Welders, grinders, generators and hand tools, on site or in the workshop.
Activities that many standard policies restrict unless declared.
If you certify, inspect or sign off welding or structural work.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us what you fabricate.
What we ask
Two welding businesses of the same size can be very different risks. These details shape your cover.
01
MIG, TIG, stick, structural steel, repairs or manufacturing.
02
Workshop, mobile, construction sites or shutdowns.
03
Whether you work at height or in confined areas.
04
Employees or subcontractors.
05
What you carry and what sits in the workshop.
06
Limits, hot-works rules and who you contract with.
Taking on mine or shutdown work? Tell your broker before you start.
Site and contract requirements
Principals usually ask for proof of Public Liability before you start. Hot works and height conditions often sit in the subcontract.
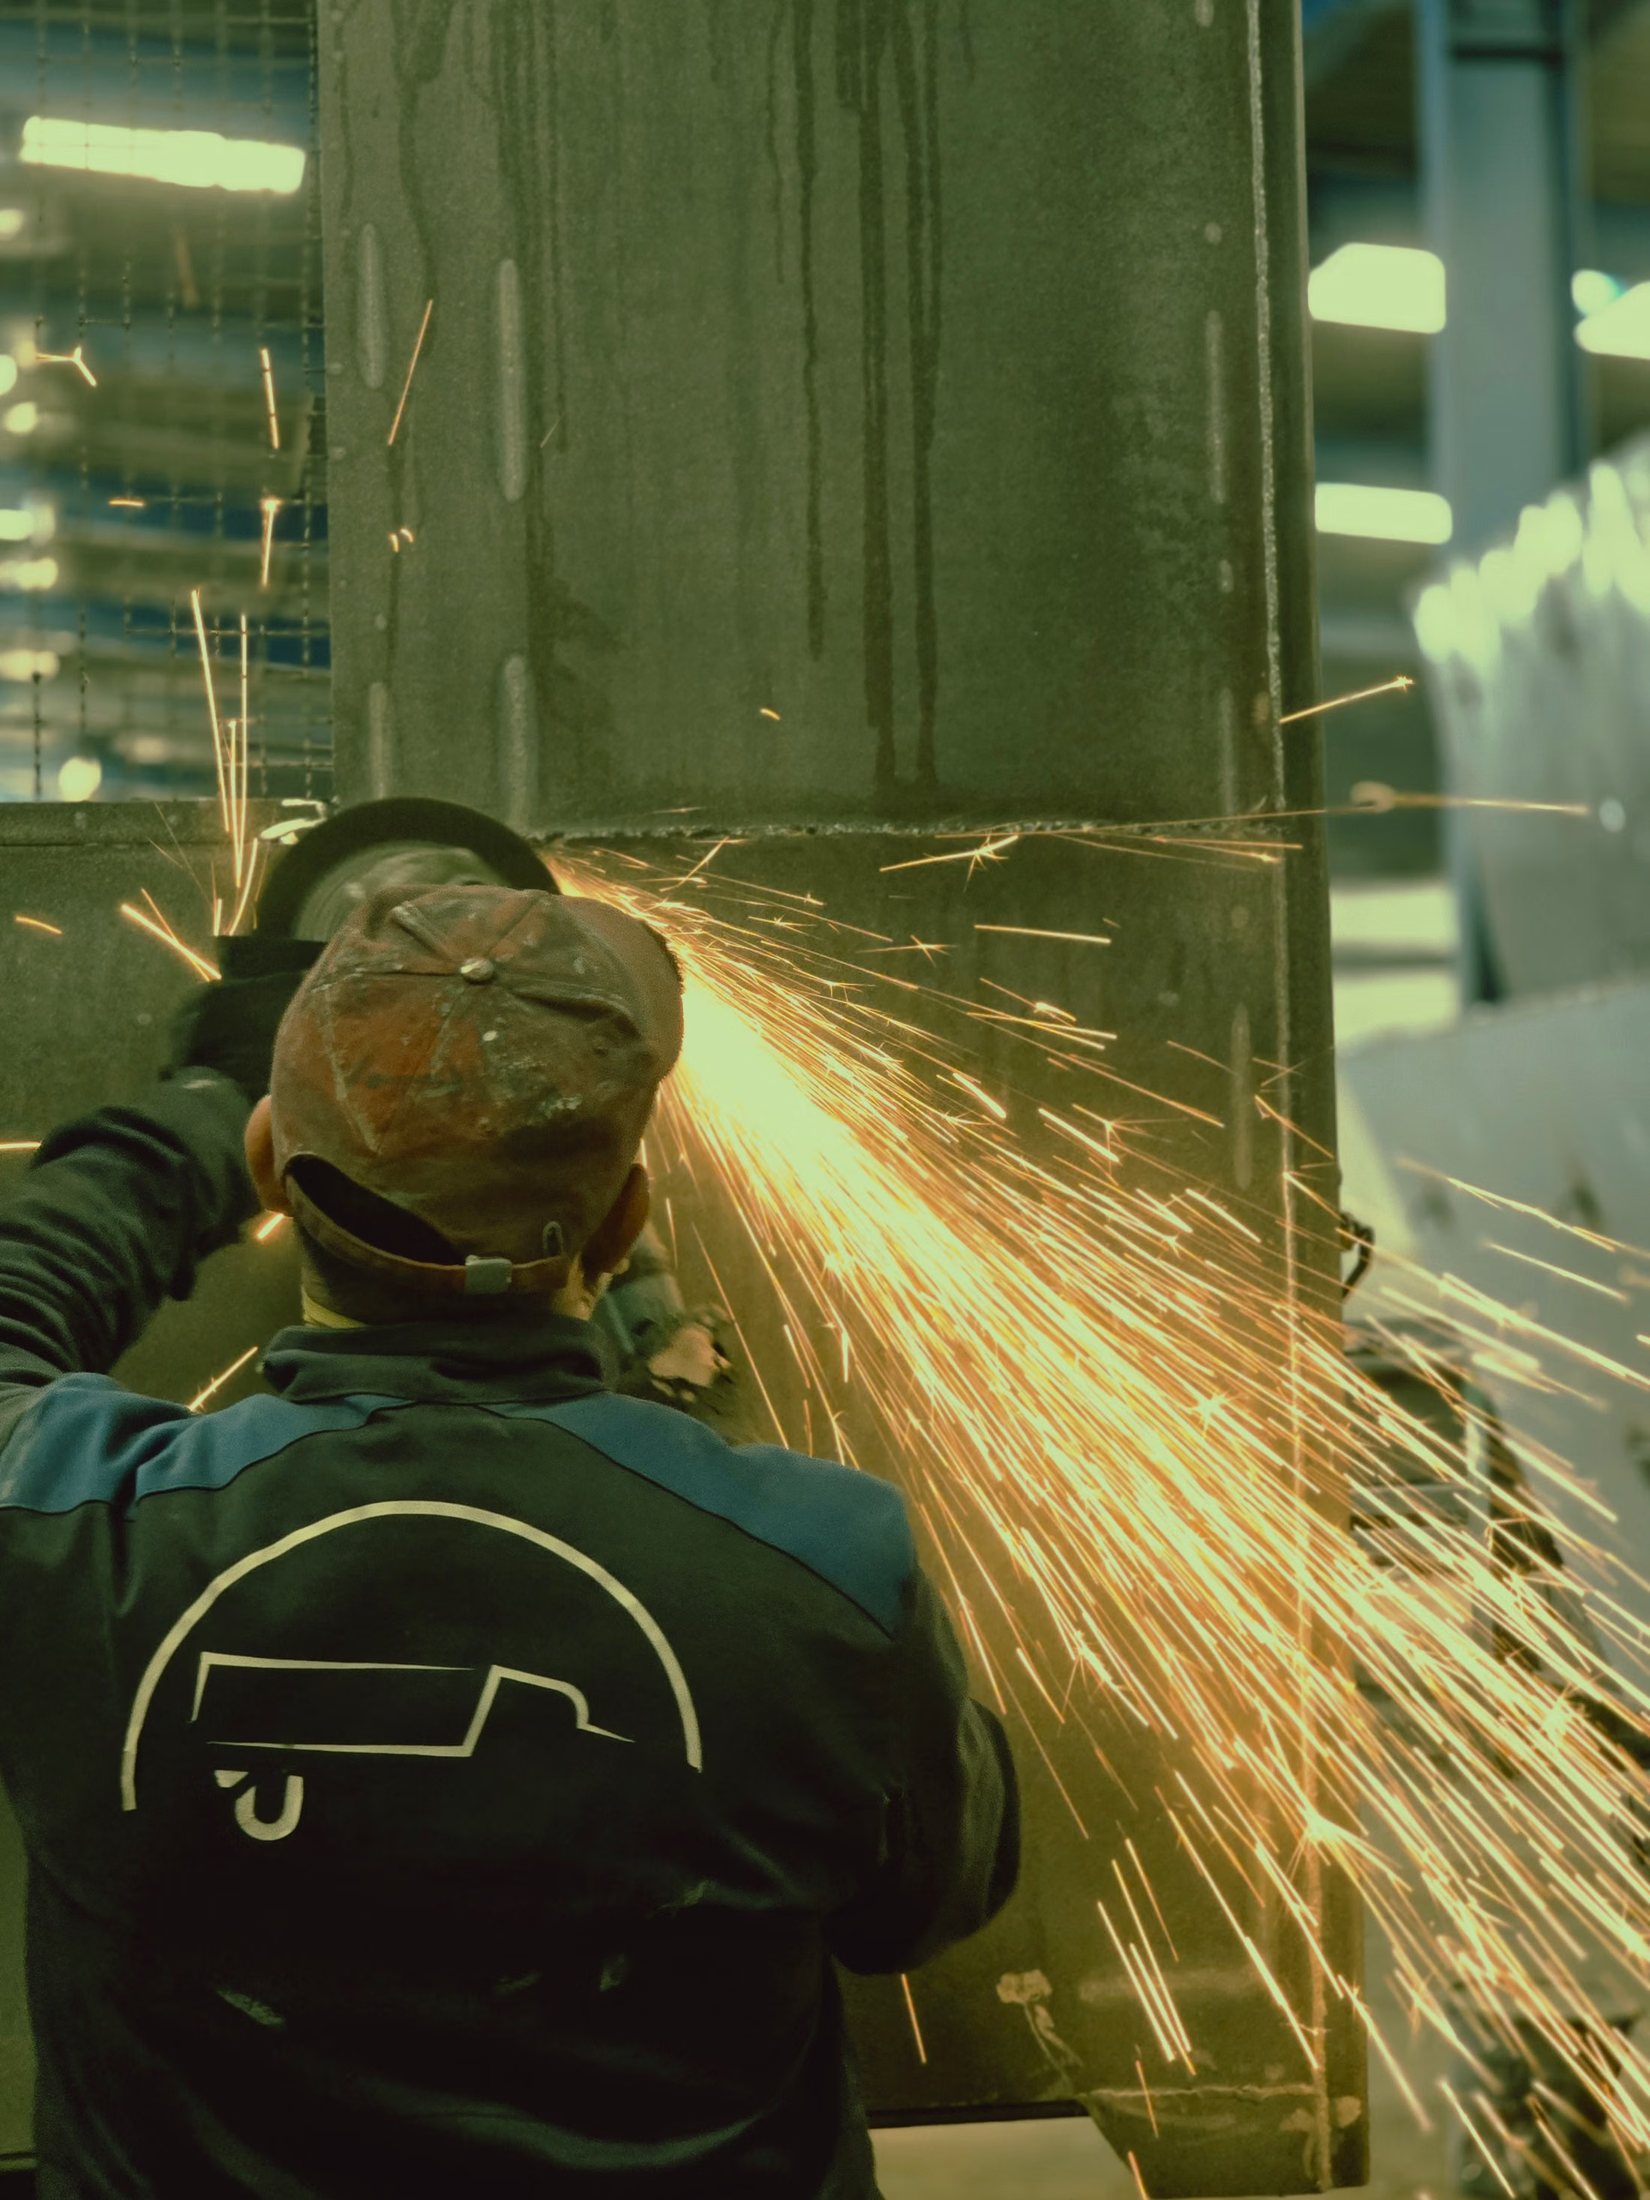
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From trade clients
What our clients say, in their own words.
Illustrative example · Boilermakers
Illustrative example, not a real client. A mobile welder who usually does farm and workshop repairs is offered work on an industrial shutdown.
We would check whether hot works and the site type are declared, what Public Liability limit the principal asks for, and whether subcontractors are listed.
The new work is declared and covered before the shutdown starts.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Priority Insurance Brokers made choosing my businesses insurance a breeze. Their team has made me a tailor made package that suits me perfectly. I’d highly recommend them to anyone”
“Super impressed with Daniel’s proactivity and turn around time. Makes it really convenient, and his advice is very helpful for someone who might not prioritise searching for insurance.”
“Nothing is too much to ask for this team. Special mention to Rodel for always getting back to us asap. Highly recommend these guys for anyone working/ running a business in the construction industry and needing to sort their insurances.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your welding work, sites, crew, tools, plant and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with trades, construction and other blue-collar businesses, and our team works the same way.
Trades
Welding
Tools
Industrial
Qualifications
FAQs
Most start with Public Liability, then add tools, vehicles and a business package if they run a workshop. Hot works and industrial sites need to be declared.
Hot works, mobile work, heights and construction subcontracting are seen as higher risk. A broker looks for insurers who will consider that work.
You may if you inspect, certify or sign off welding or structural work. Pure fabrication without advice often does not need it.
Not always. Many policies restrict or exclude hot works unless they are declared and the conditions are met.
Yes. Insurers ask about subcontractors because they change your cover and premium. Some policies exclude claims from uninsured or undeclared subcontractors.
Often yes. Liability can be packaged with tools, equipment and trailers, including transit and onsite storage, depending on the wording.
Before you start trading on your own. Work you do through your own business isn’t covered by an employer’s policy.
It depends on your work type, sites, hot works, crew size, turnover, tools, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.