Related work
Industry insurance · Warehouse and Distribution
Brisbane-based, Australia-wide brokers for warehouses, 3PLs and distribution centres. Tell us what you store, who owns it and how goods come in and go out.
Warehouse insurance at a glance
Racking, offices and docks.
Your goods and customers’.
Visitors, drivers and products.
Income after damage.
The basics
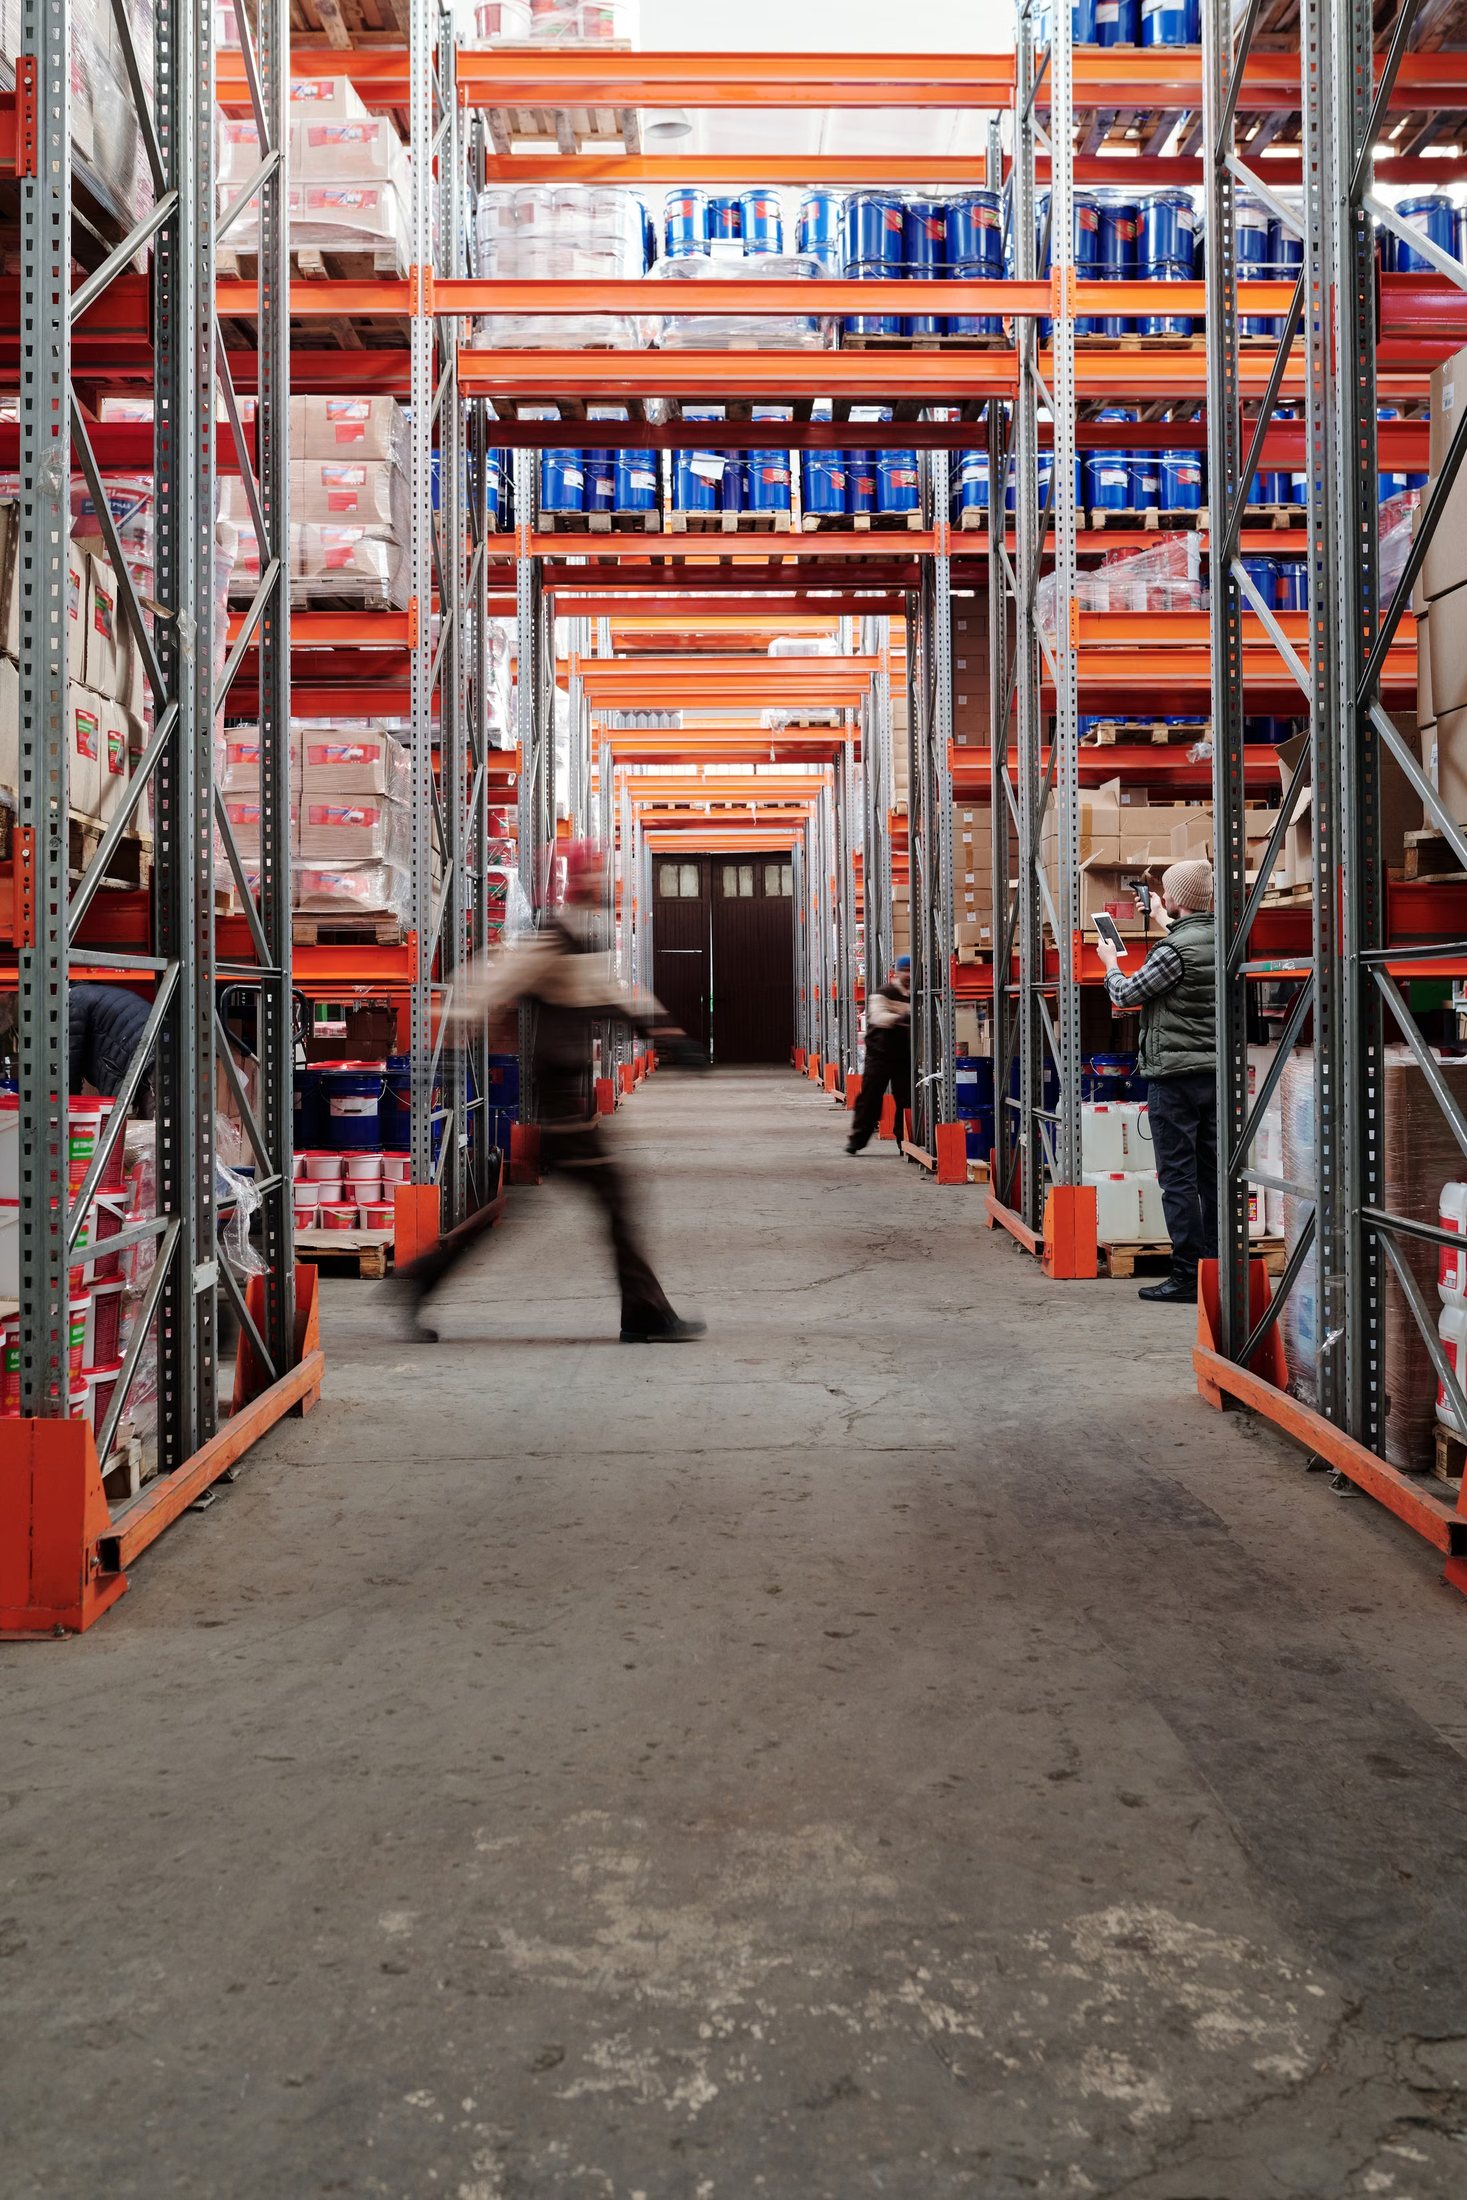
Warehouse and distribution insurance is the mix of covers a storage business needs. The building, fitout, stock, machinery and liability may belong to different parties.
Insurers look at what you store, storage height, racking, fire protection, forklifts, battery charging and who owns each asset.
Building, fitout and racking.
Your stock and customers’.
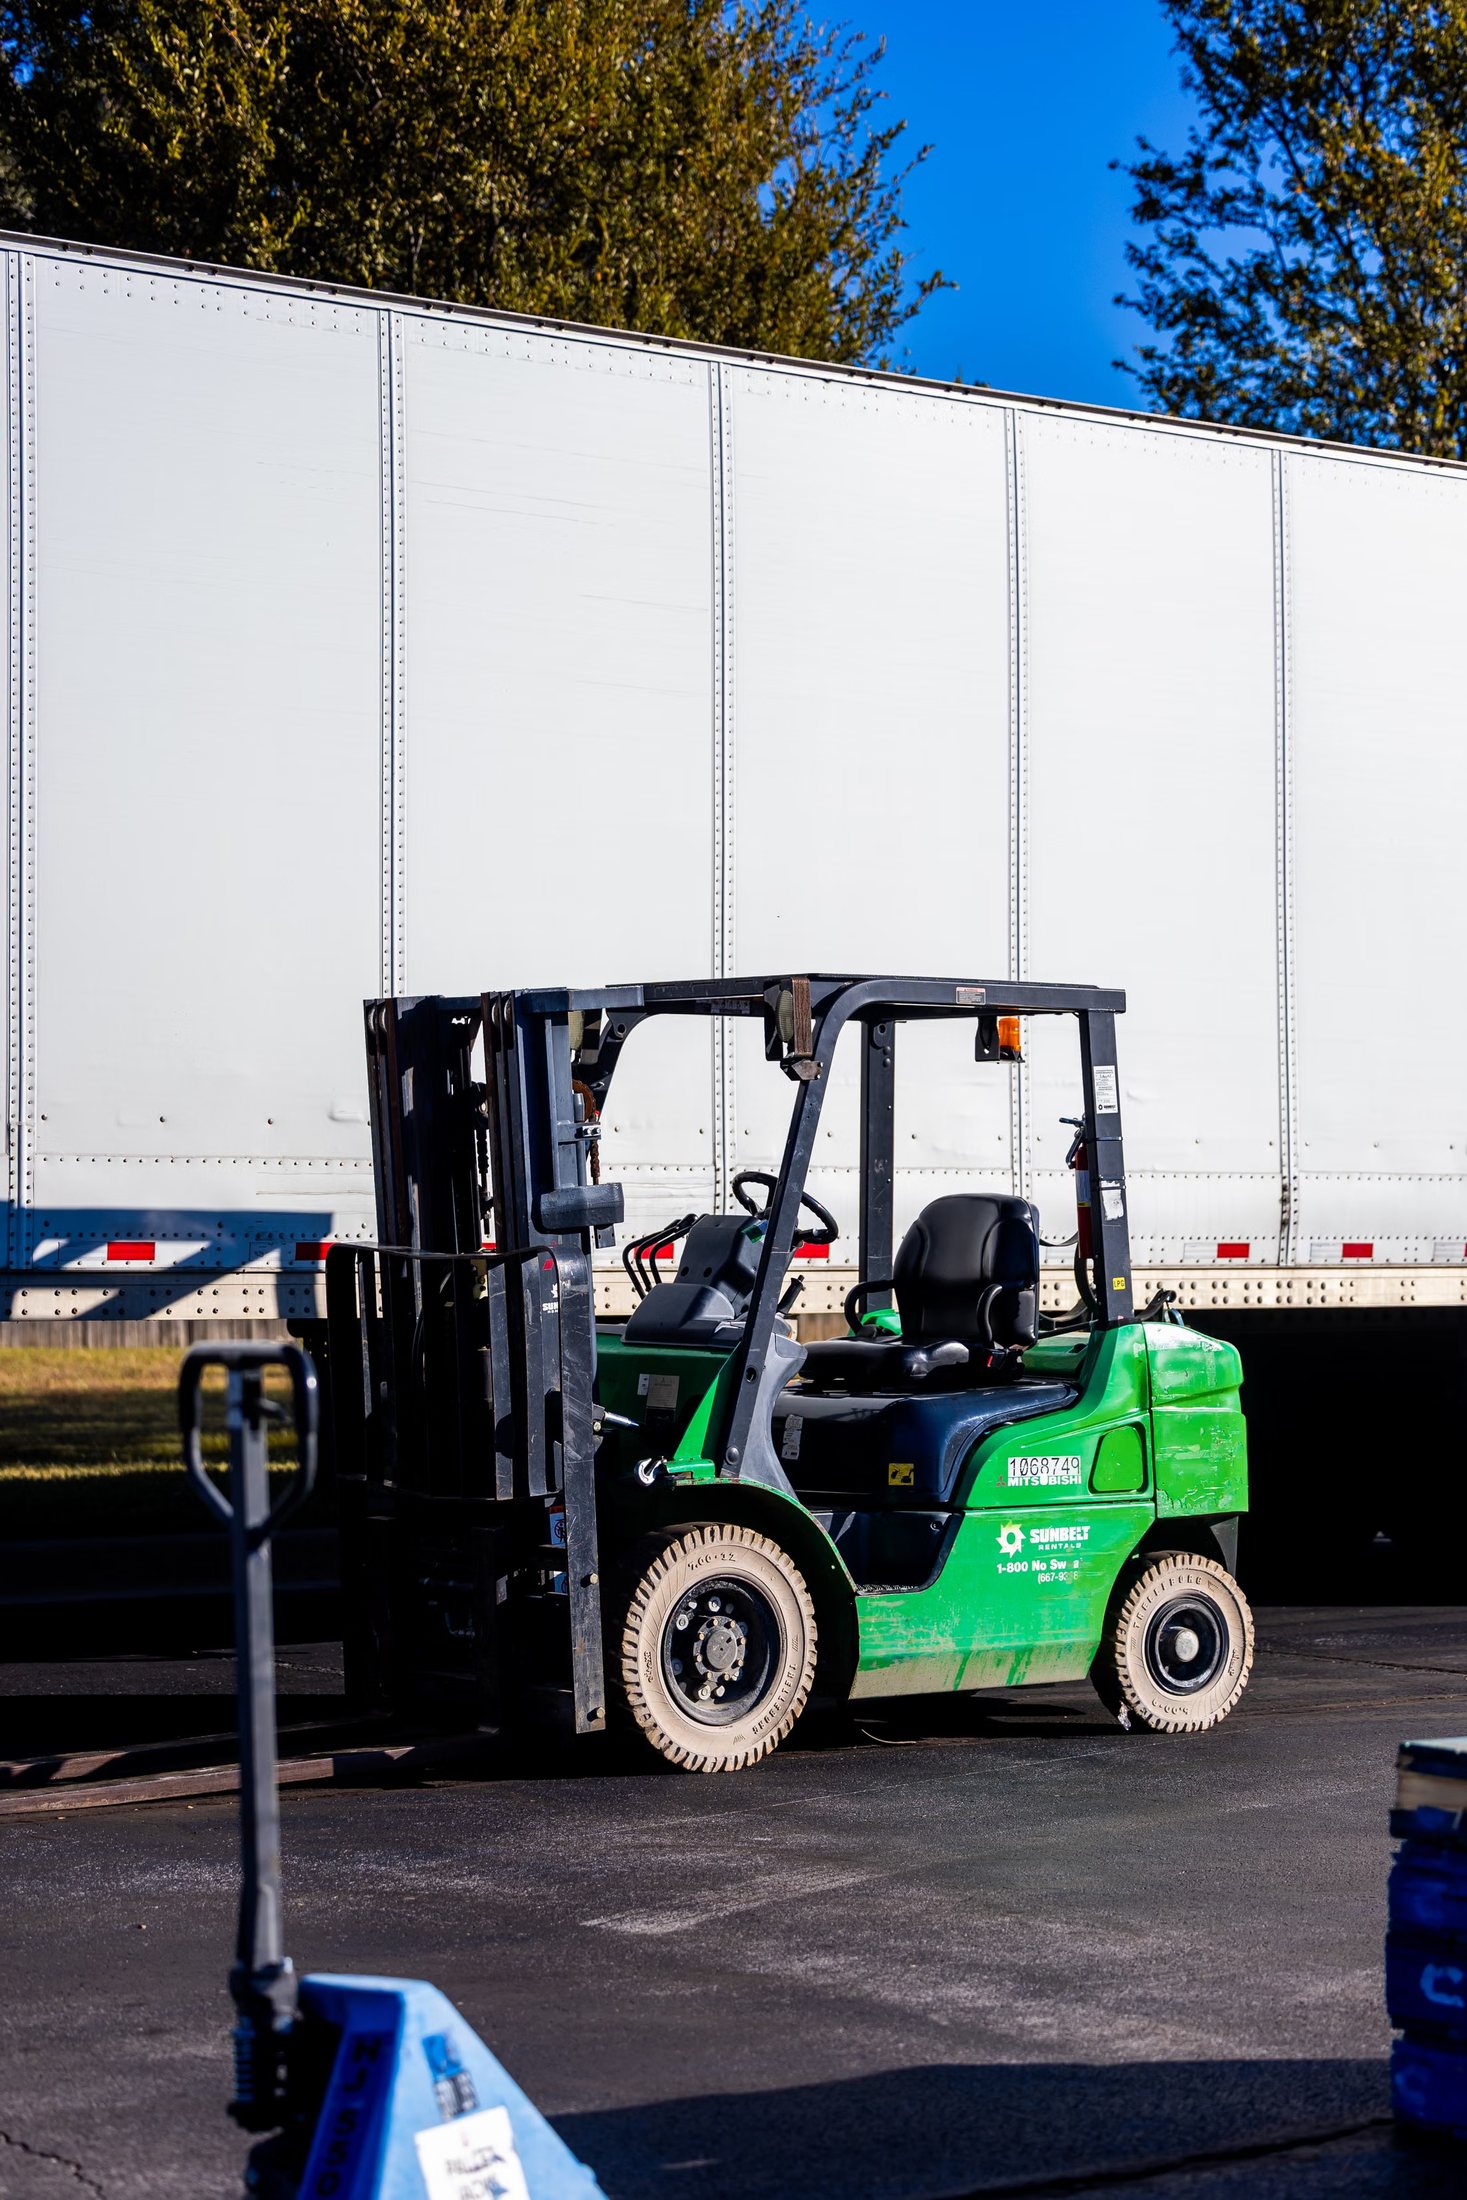
Forklifts, docks and delivery.
Cover that maps who owns what.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
One site storing your own or customers’ goods. Start with property and liability.
Larger sites with fleets, forklifts and high stock values.
Cover options
Most warehouse businesses need a mix, not every policy. Your broker helps you choose what fits.
Building, fitout, racking and stock, including larger sites.
Claims from injury to visitors and drivers, or damage to others’ property.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us about your site.
What we ask
Two warehouses of the same size can be very different risks. These details shape your cover.
01
Goods, hazards and values.
02
Your stock or customers’.
03
Racking layout and height.
04
Sprinklers, alarms and hydrants.
05
Owned, leased and charging.
06
What the landlord insures.
Storing hazardous goods or running a cool room? Tell your broker early.
Contract requirements
Landlords and customers usually ask for proof of cover. The lease or contract often names limits and who insures what.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From transport clients
What our clients say, in their own words.
Illustrative example · Warehousing
Illustrative example, not a real client. A business storing its own stock leases more space and starts storing and dispatching goods for other companies.
We would check how customers’ goods are covered, the lease terms, racking and forklifts, and the new contracts.
Customers’ goods and the new space are covered.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Very happy with the service provided and rates quoted with Priority! They are great to deal with and always get back to me very quickly. Thanks for your on going support with my company and personal insurance needs.”
“Had a wonderful experience with Daniel from Priority Insurance Brokers. I sent him a message in the morning and had a response within a few minutes. My new policy was drawn up and sent to me the same day. Even though insurance is a disgusting industry, I am glad there are still good people in there to help us navigate through it. Thanks again Daniel and the team!”
“Seemless service from Dan when I’d realised I’d forgotten to pull the trigger on a quote for business insurance. A small handful of emails and a quick comparison to my prior quote, he’d recognised that the cover initially quoted to me was severely lacking for my business operations, found the right policy and working with peace of mind again in not time at all. Talk about feeling like a priority! Thank you!”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your site, stock, racking, forklifts, lease and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with transport, construction and other blue-collar businesses, and our team works the same way.
Logistics
Property
Liability
Forklifts
Qualifications
FAQs
Generally no. Landlords usually insure the building. Your stock, fitout and racking need your own cover.
Only if your policy covers goods in your care. Tell us whose goods you hold and their values.
When values or complexity outgrow standard business policies. ISR can give broader cover and higher limits.
Not always. Forklifts can need their own cover, especially when they’re used outside the building.
Yes. The lease can pass insurance or repair obligations to you, so send us the lease before you sign.
Not under a property policy. Stock on the road needs goods in transit cover.
If you employ drivers or other workers, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on what you store, its value, the building, fire protection, forklifts, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.