Related work
Industry insurance · Dangerous Goods Transport
Brisbane-based, Australia-wide brokers for carriers of fuel, chemicals, gases and other dangerous goods. Tell us what you carry, how you’re licensed and what your contracts ask for.
DG insurance at a glance
Injury and damage to others.
Spills and clean-up.
Tankers, prime movers and rigids.
What sites and customers ask for.
The basics
Dangerous goods transport insurance pairs motor cover with liability that deals with spills, fire and pollution. Fewer insurers write this work, so the submission matters.
Insurers check your classes and quantities, licensing, driver qualifications, equipment and whether you store goods or only carry them.
Tankers and other DG units.
Third-party injury and damage.
Where spill cover sits.
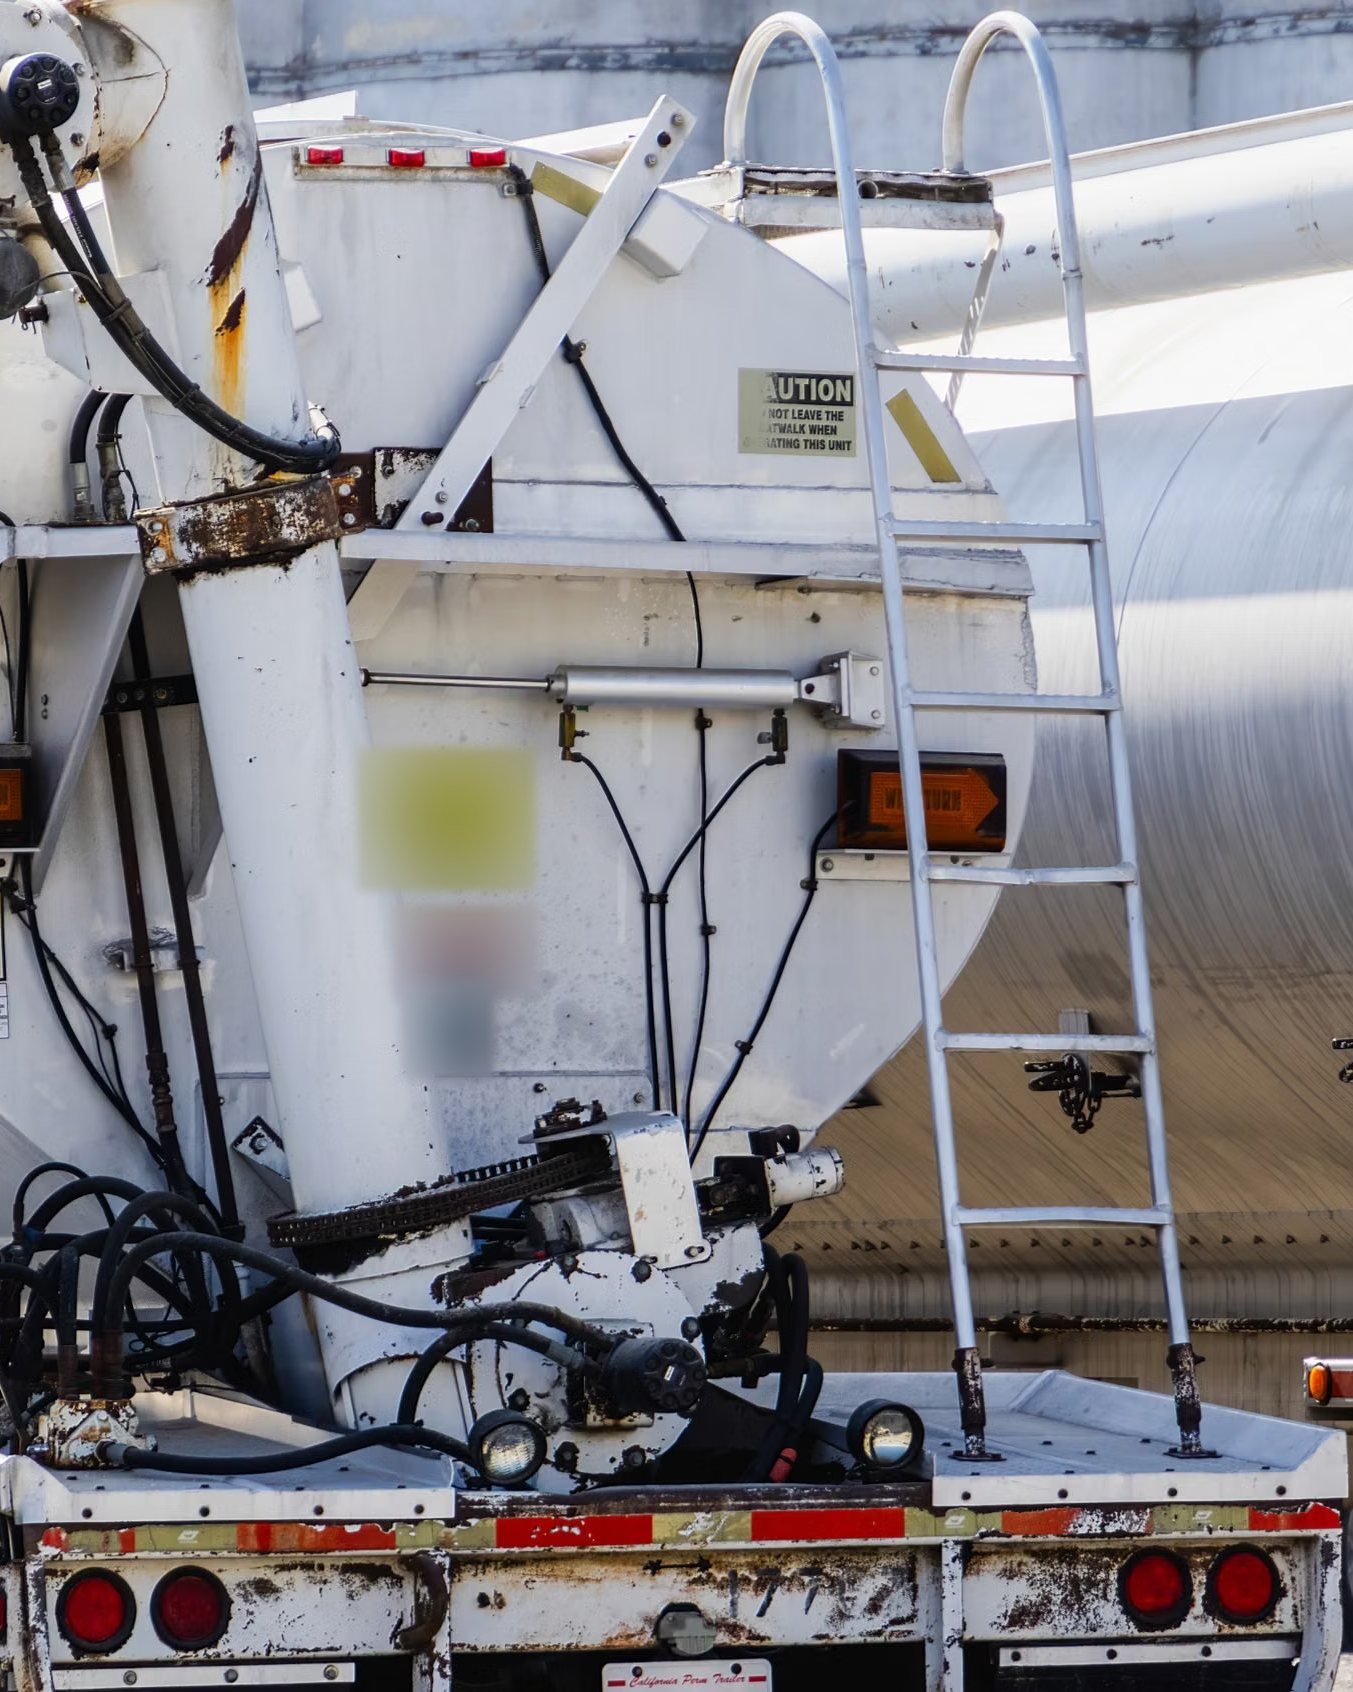
Cover that matches what you carry.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Cover options
Most DG carriers need a mix, not every policy. Your broker helps you choose what fits.
Claims from injury or property damage caused by your DG work.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us about your loads.
What we ask
Two DG carriers with the same truck can be very different risks. These details shape your cover.
01
Classes and quantities of goods.
02
Vehicle and driver DG licensing.
03
Tank age, design and maintenance.
04
Point-to-point only, or held overnight.
05
Metro, regional or interstate.
06
Limits and endorsements required.
Moving into DG work for the first time? Tell your broker before the first load.
Contract requirements
Terminals, fuel companies and major sites commonly ask for higher limits and specific wording before you’re allowed on site.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From transport clients
What our clients say, in their own words.
Illustrative example · Dangerous goods
Illustrative example, not a real client. A general freight carrier wins work moving packaged chemicals point to point, with no storage along the way.
We would check the classes carried, licensing, the liability limit the contract asks for and how pollution is covered.
The DG work is declared before the first load.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“By far the most ethical business I’ve ever dealt with. Daniel got us out of a bind a few years ago. These guys now handle all our business and personal policies. I can’t recommended highly enough..”
“Quick, honest and reliable insurance brokers with a competitive rate. I needed a quote on the day and they sorted it on the same day to, getting me out of trouble. Appreciate the work and speed they could get this done, I recommend them very highly”
“Daniel has been absolutely fantastic and prompt in dealing with out commercial vehicle insurance and now our Public Liability and business insurance needs. I would highly recommend Daniel & the team for your insurance needs – no fuss, diverse options and found us the lowest premium to suit our needs.”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your vehicles, DG classes, licences, routes and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with transport, construction and other blue-collar businesses, and our team works the same way.
Transport
Dangerous goods
Liability
Complex risks
Qualifications
FAQs
Often, yes. Many insurers don’t write DG carriage, so it usually needs a specialist market and a clear submission.
Not necessarily. Pollution and clean-up may need liability cover or an endorsement. Check where spill cover sits before you rely on it.
The Australian Dangerous Goods Code sets requirements for transport by road and rail. State and territory laws give it legal force.
Yes. Carrying goods point to point is a different risk from storing them, so tell your broker if you hold loads overnight.
Not under motor or liability cover. The goods you carry need their own transit cover, and the contract may say who arranges it.
Yes. If the work on your policy doesn’t match what you actually do, the policy may not respond to a claim. Describe the whole operation.
If you employ drivers or other workers, you’ll generally need workers’ compensation in your state or territory. Check your state’s rules.
It depends on what you carry, quantities, vehicles, licensing, routes, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
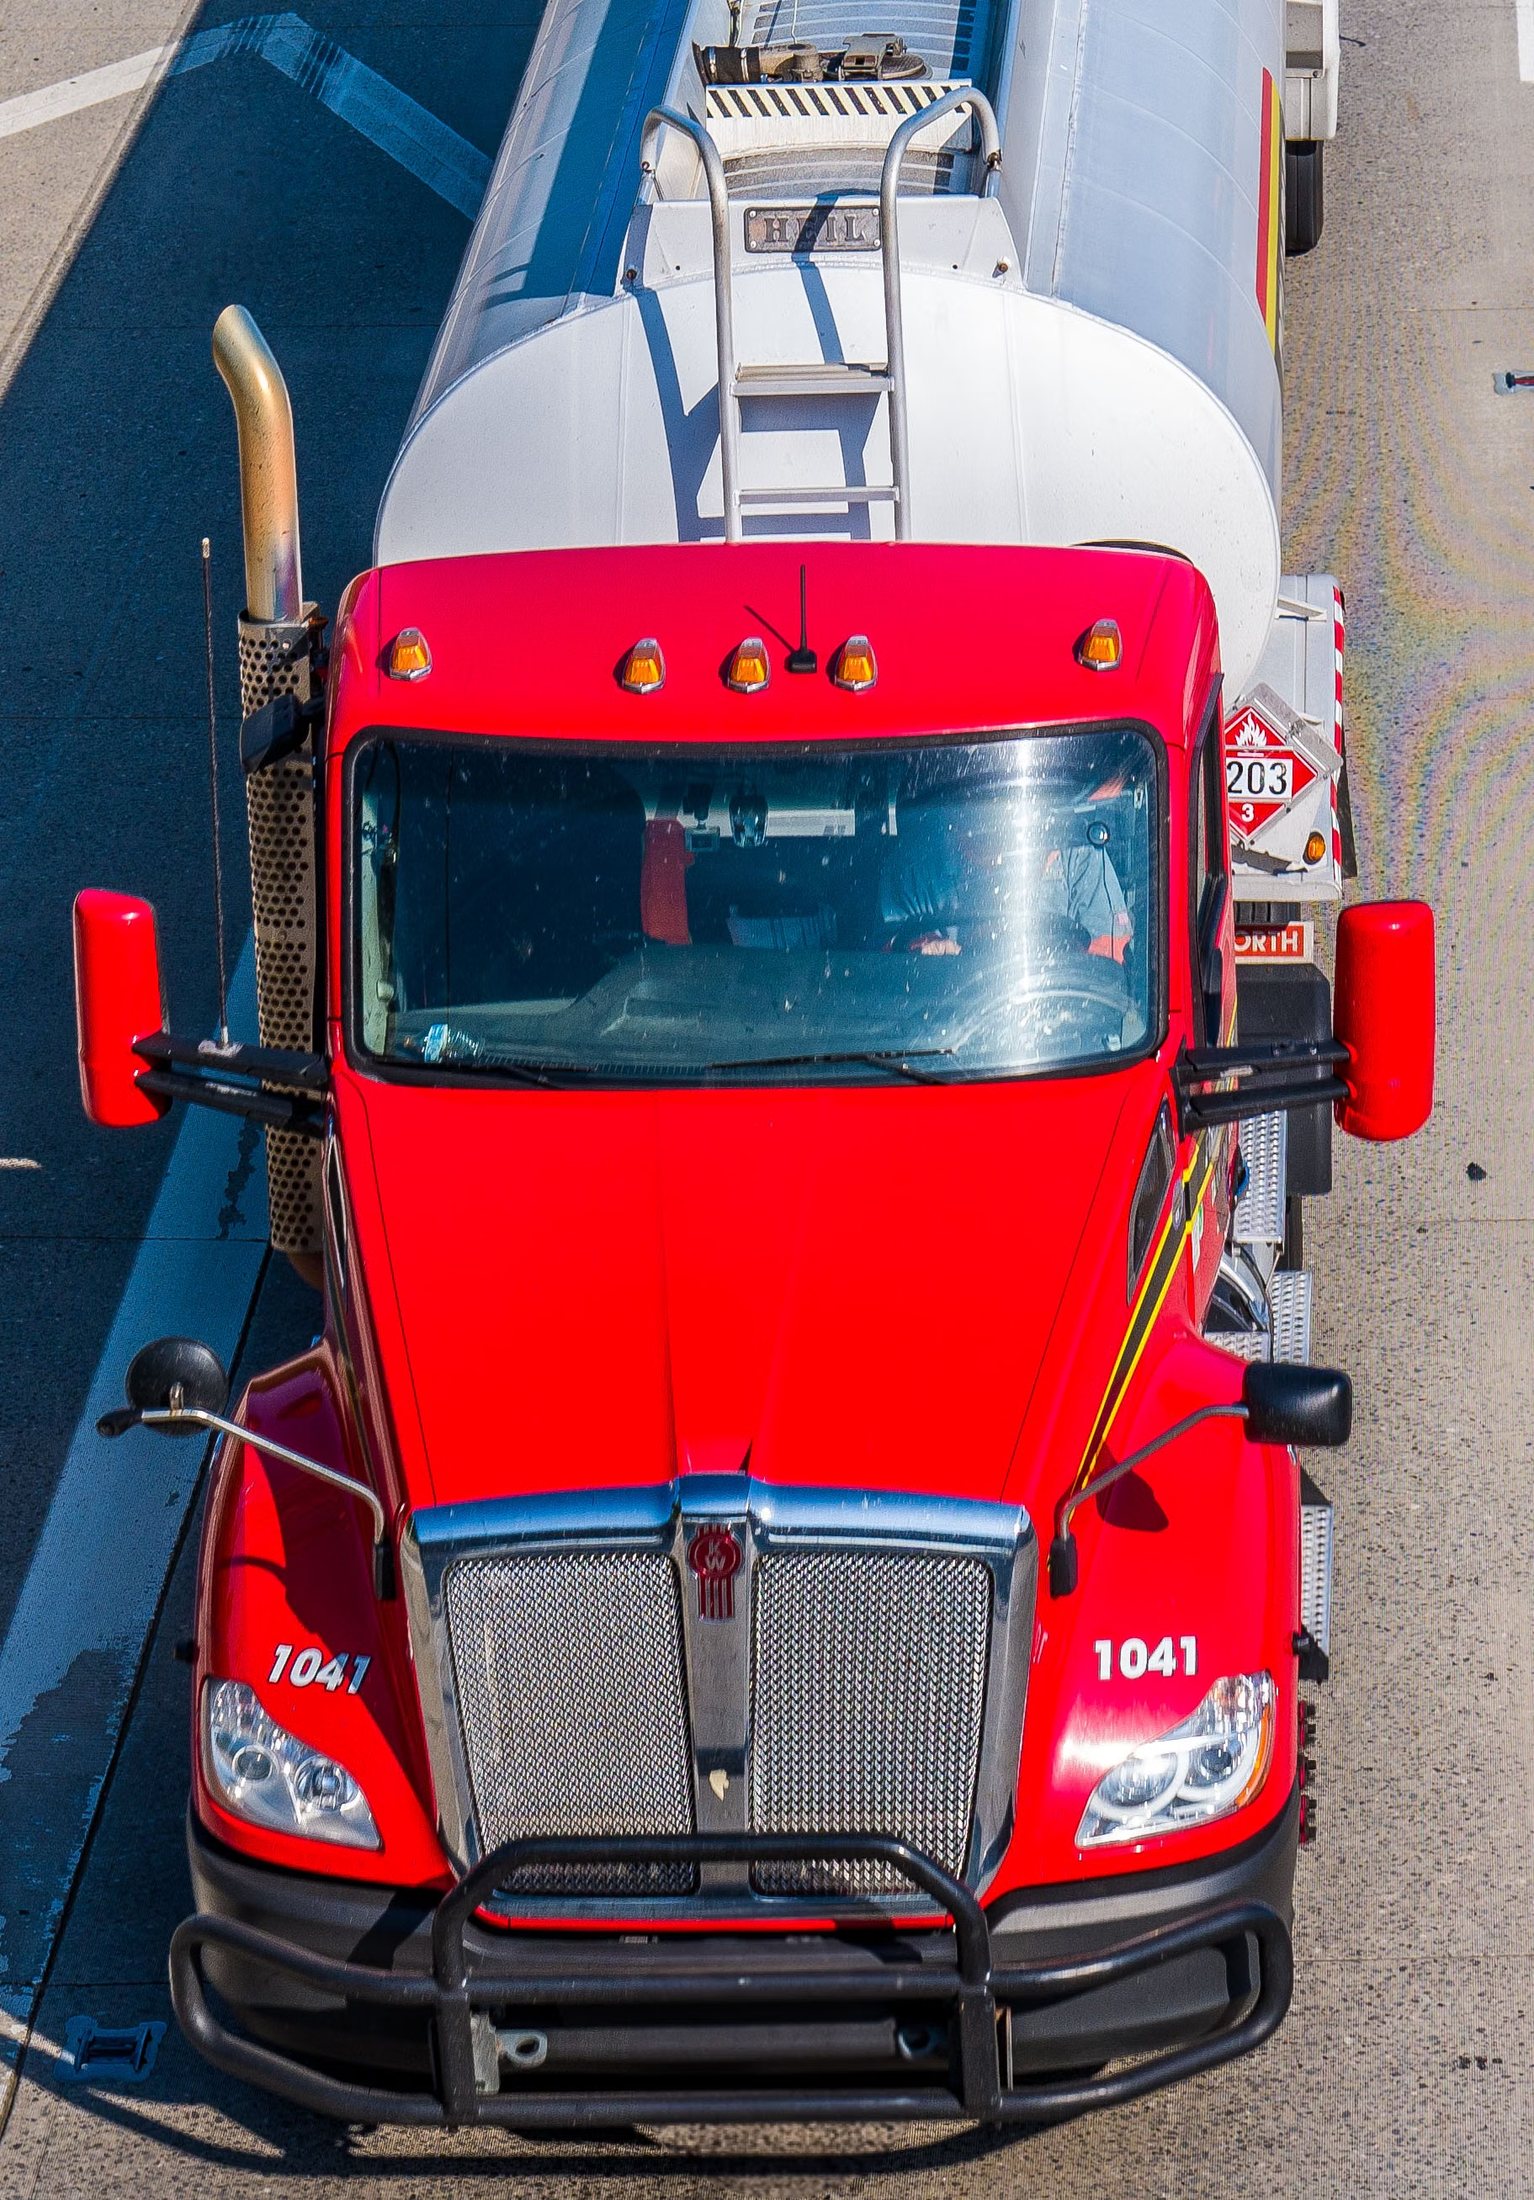
Photo credits: Banner photo by W. Bulach, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.