Related trades
Industry insurance · Flooring Contractors
Brisbane-based, Australia-wide brokers for flooring contractors. Tell us what you install, whether you sand or grind, and the sites you work on, and we’ll help you set up the right covers.
Flooring insurance at a glance
Injury or damage from install work.
Sanders, grinders, cutters and hand tools.
Sanding, grinding and adhesives.
What builders and owners ask for.
The basics
Flooring installers insurance is the mix of covers a flooring business needs. Timber, vinyl, carpet, epoxy and polished concrete each bring different site and product risks.
Dust from sanding or grinding, adhesive spills and damage to existing finishes are common claim themes, so how you prep and what you install should be declared.
Claims linked to install or prep work.
Sander, grinders and the ute.
Limits and who you contract with.
Cover that matches how you install.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Shopping centres, offices or high-limit contracts.
Cover options
Most flooring businesses need a mix, not every policy. Your broker helps you choose what fits.
Claims that your work injured someone or damaged property, including existing floors and finishes.
Only if you specify systems, certify moisture or sign off work.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us what you install.
What we ask
Two flooring businesses of the same size can be very different risks. These details shape your cover.
01
Timber, vinyl, carpet, epoxy, polished concrete or hybrid.
02
Sanding, grinding, levelling or moisture testing.
03
Employees or subcontractors.
04
Sanders, grinders and what you leave on site.
05
Homes, units, retail or larger commercial sites.
06
Limits, indemnities and who you contract with.
Starting polished concrete or heavy grinding? Tell your broker before you quote.
Site and contract requirements
Builders usually ask for proof of Public Liability before you start. The subcontract often names a limit.
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From trade clients
What our clients say, in their own words.
Illustrative example · Flooring
Illustrative example, not a real client. A timber flooring crew is offered polished concrete work in a retail tenancy.
We would check whether grinding and concrete polishing are declared, what dust controls the insurer expects, and what the builder’s subcontract asks for.
The new activity is declared before the first grind.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Daniel was great to deal with, super understanding with my lack of knowledge and knew exactly what I needed! Highly recommend!”
“Quick, honest and reliable insurance brokers with a competitive rate. I needed a quote on the day and they sorted it on the same day to, getting me out of trouble. Appreciate the work and speed they could get this done, I recommend them very highly”
“Ben was fantastic, quick and easy service. Would 100% recommend”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your surfaces, prep methods, crew, tools and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with trades, construction and other blue-collar businesses, and our team works the same way.
Trades
Flooring
Tools
Fit-out
Qualifications
FAQs
Most start with Public Liability and tool cover, then add vehicles and contract works. Products and subcontractors should be declared.
It can, depending on the wording and how the damage happened. Faulty workmanship to fix your own work is often treated separately.
Tell your broker about sanding and grinding. Dust-related damage and respiratory risks are part of how the work is assessed.
Yes. Insurers ask about subcontractors because they change your cover and premium. Some policies exclude claims from uninsured or undeclared subcontractors.
It can be. Grinding and concrete polishing should be named so the policy matches the work.
Usually only if you specify systems, certify moisture or sign off work for others.
Before you start trading on your own. Work you do through your own business isn’t covered by an employer’s policy.
It depends on your surfaces, prep methods, crew size, turnover, tools, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
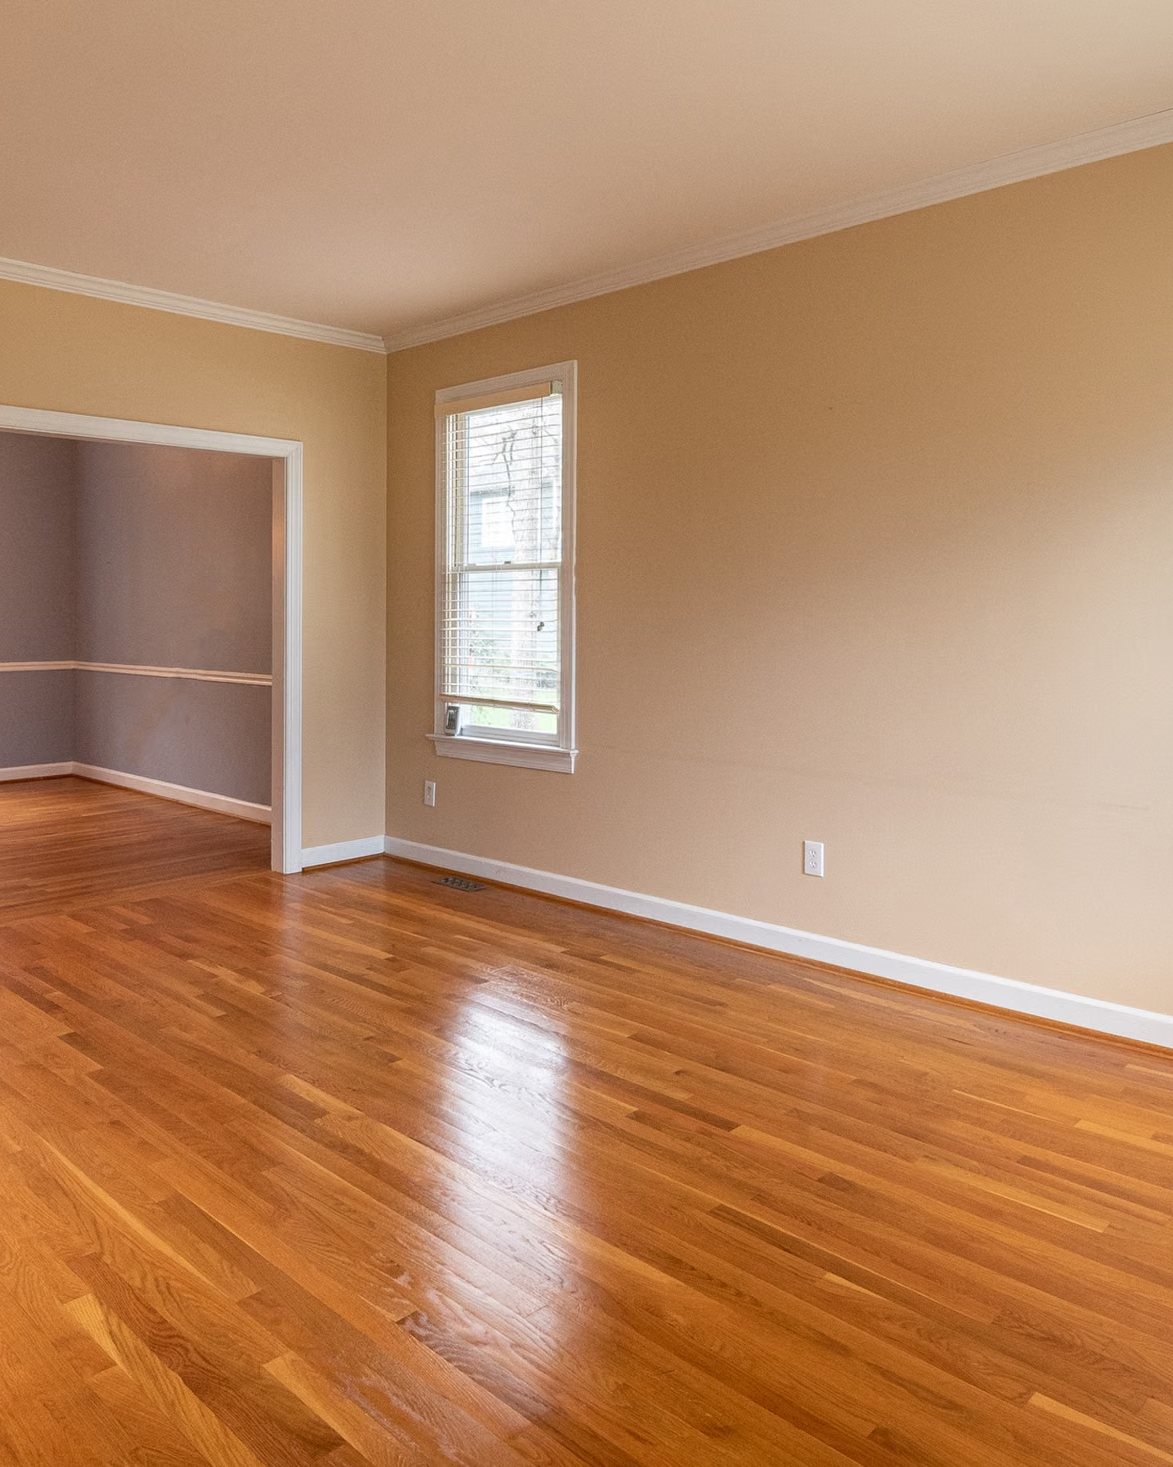
Photo credits: Top photo by Kgbo, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.