Related trades
Industry insurance · Shopfitters
Brisbane-based, Australia-wide brokers for shopfitters. Tell us the fit-outs you take on, whether you design, and who works with you, and we’ll help you set up the right covers.
Shopfitters insurance at a glance
Injury or damage during a fit-out.
Saws, fixings and site tools.
Custom joinery and drawings.
What landlords and builders ask for.
The basics
Shopfitters insurance is the mix of covers a retail or commercial fit-out business needs. Strip-outs, joinery, glazing interfaces and after-hours centre work each change the risk.
Public Liability is usually required before you start on a tenancy. Professional indemnity matters if you design or take design-and-construct responsibility.
Claims linked to fit-out work on site.
Tools, joinery and the ute.
Limits, design responsibility and access rules.
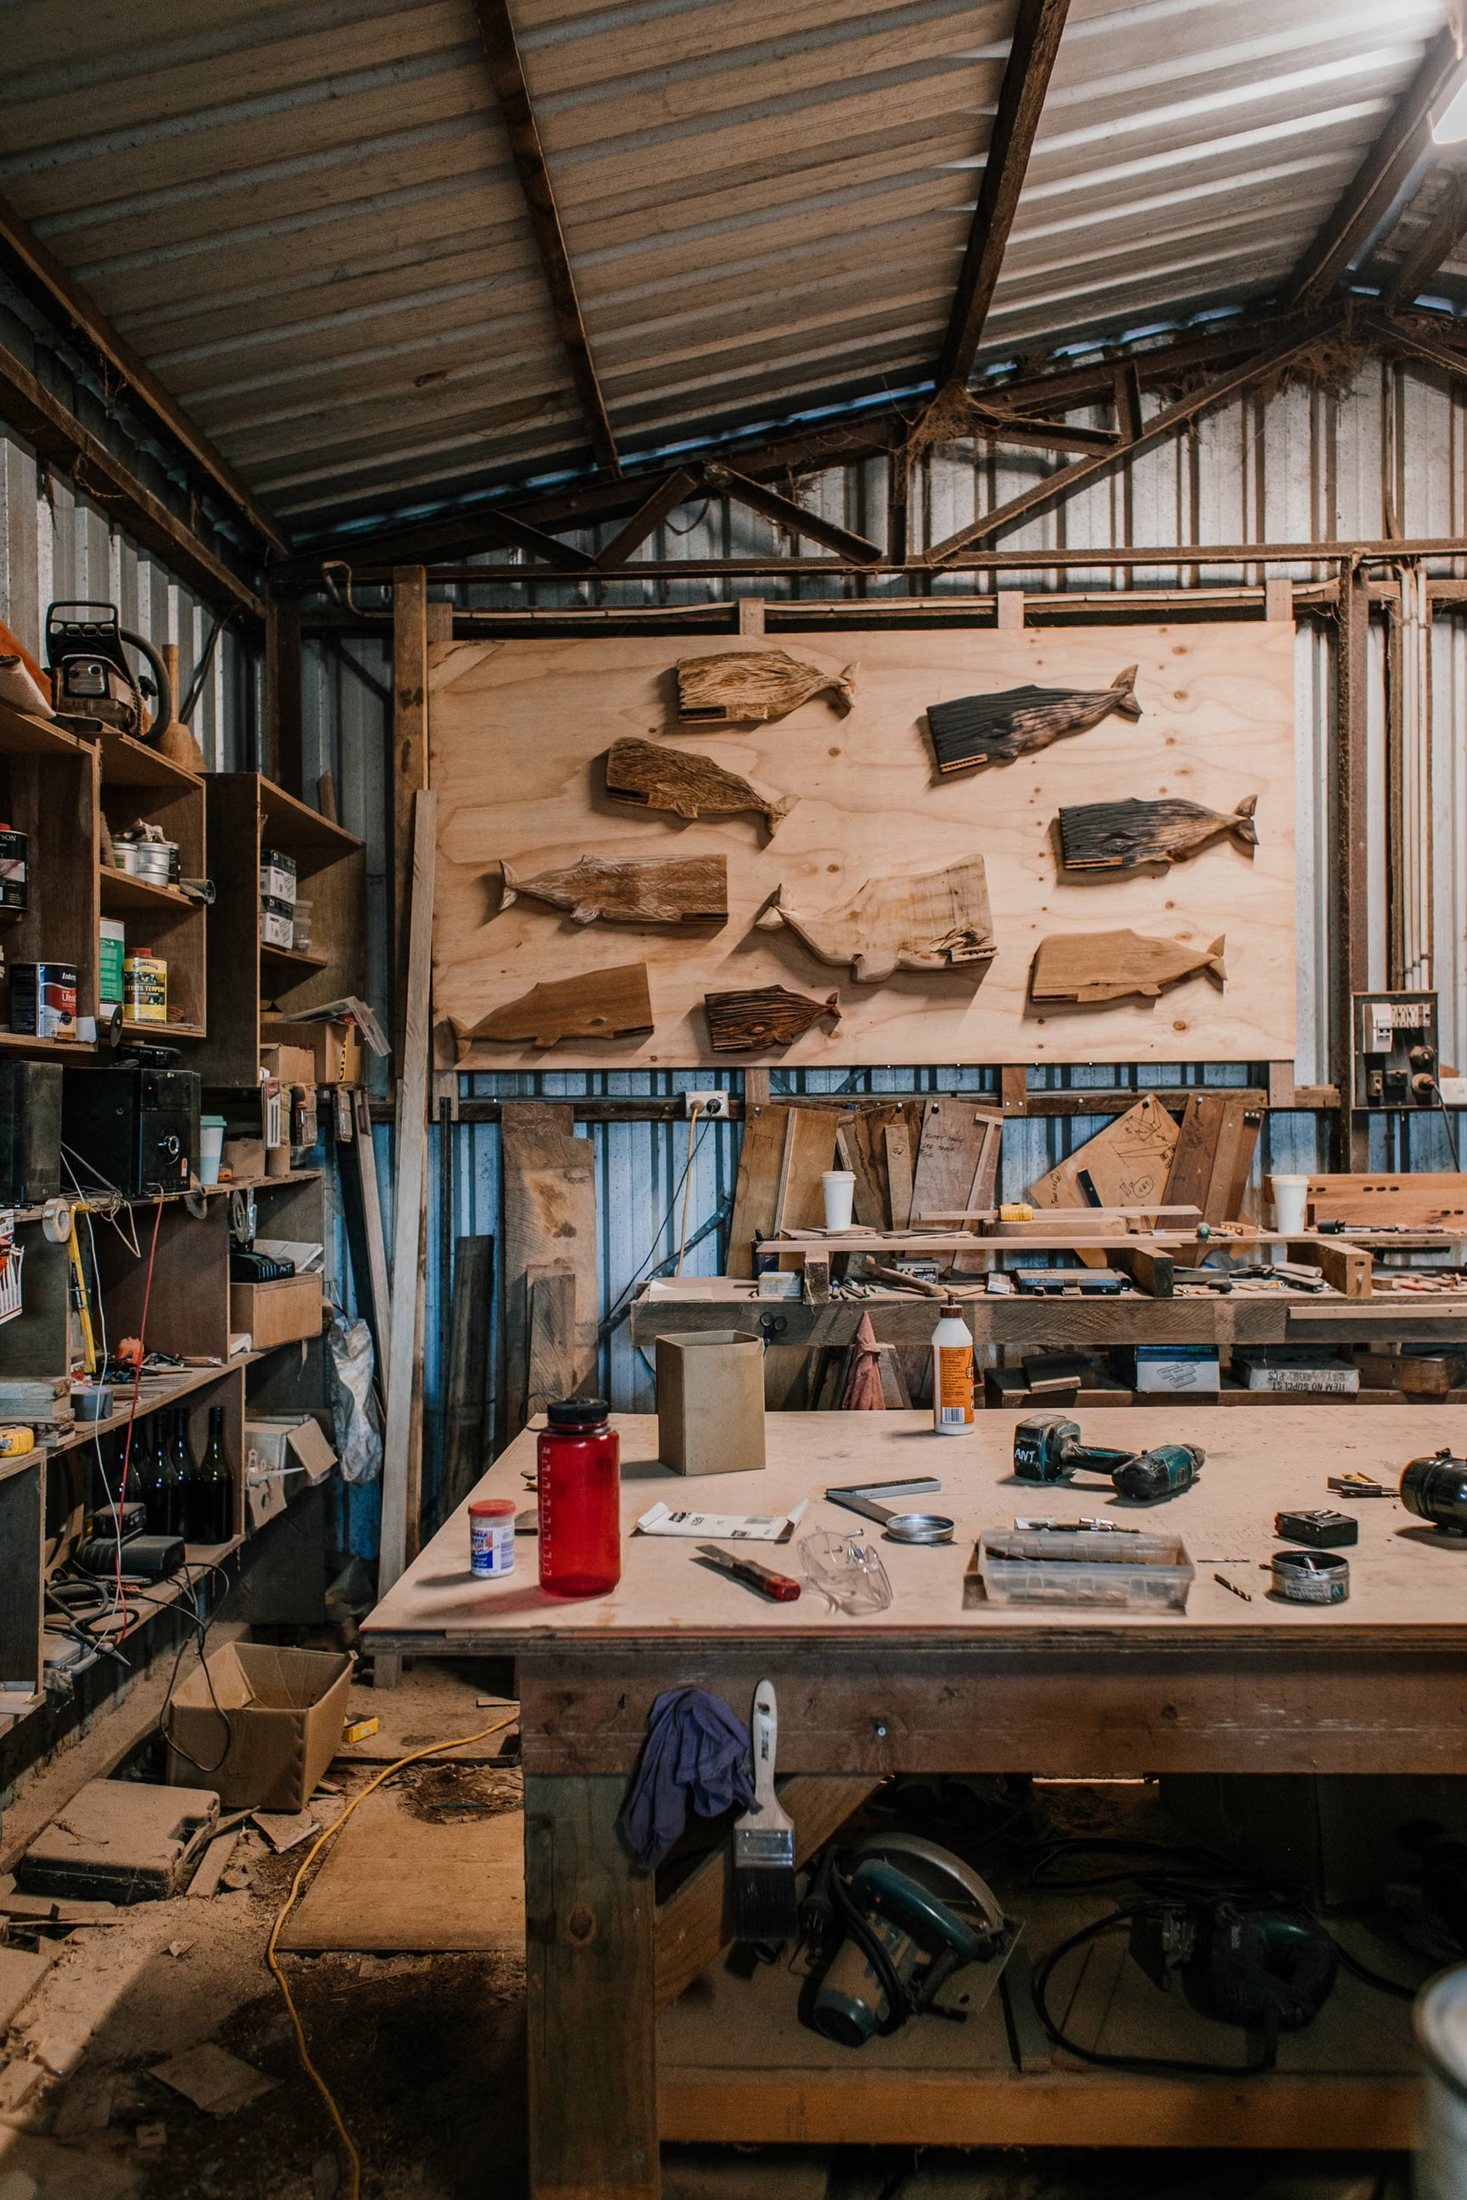
Cover that matches how you fit out.
Your business
Insurance needs grow with the business. Start with the option closest to how you work today.
Carpenters, electricians or specialists under one review.
Drawings, custom joinery or D&C responsibility that may need PI.
Cover options
Most shopfitting businesses need a mix, not every policy. Your broker helps you choose what fits.
Claims that your work injured someone or damaged property in a tenancy or centre.
Theft or damage to your tools, on site, in the ute or in storage.
Claims about design, drawings or design-and-construct responsibility.
Risks of running a company, and cyber incidents that stop work.
General information only. Cover depends on the insurer and the policy wording.
Related pages
Choose a related page, or tell us what you fit out.
What we ask
Two shopfitting businesses of the same size can be very different risks. These details shape your cover.
01
Retail, hospitality, office, medical or display.
02
Install only, or design and construct.
03
Employees or trade subcontractors.
04
Any joinery shop, machines and stock.
05
Shopping centre rules and night works.
06
Limits, indemnities and landlord requirements.
Taking on design-and-construct for a tenancy? Tell your broker before you sign.
Site and contract requirements
Builders and centre managers usually ask for proof of Public Liability before you start. Design roles may also need PI evidence.
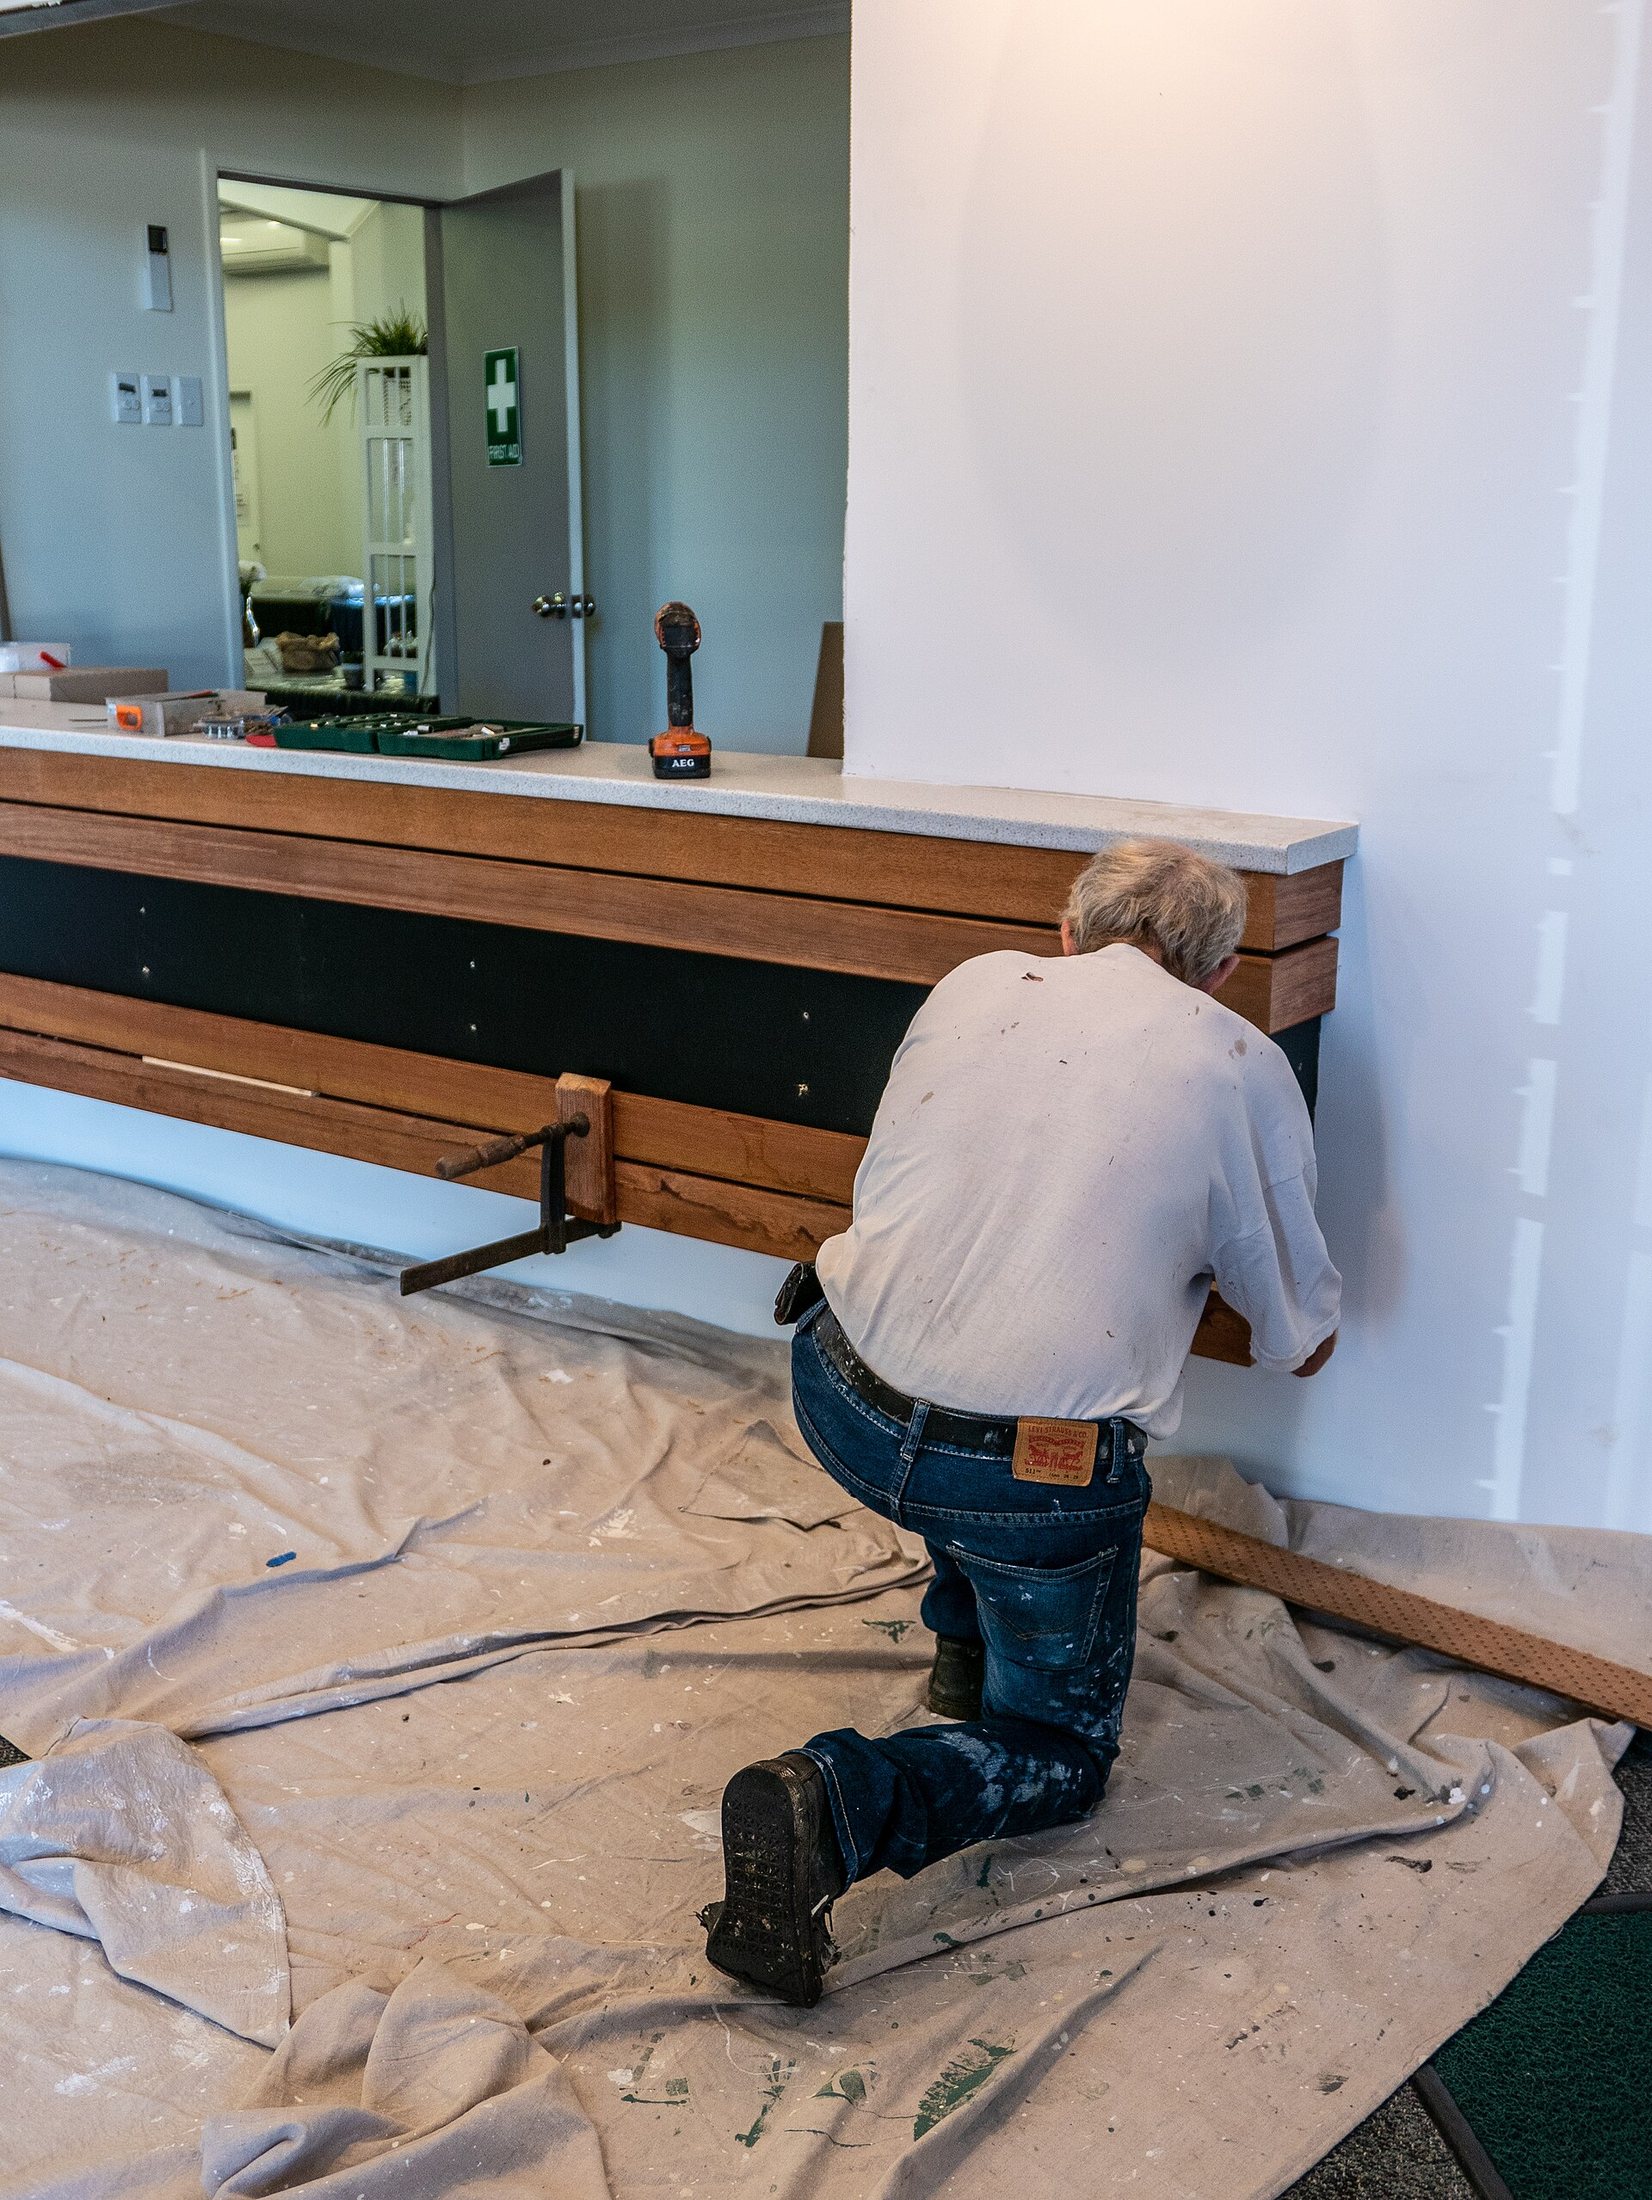
A certificate of currency confirms a policy is in force. It doesn’t prove every contract requirement is met, so send us the details.
From trade clients
What our clients say, in their own words.
Illustrative example · Shopfitters
Illustrative example, not a real client. A shopfitter who has always built to an architect’s drawings is offered a design-and-construct cafe fit-out.
We would check whether professional indemnity is in place, how design responsibility is described, and what the landlord’s rules ask for.
Design exposure is declared before drawings are issued.
Individual outcomes depend on the circumstances, insurer appetite and policy terms. This example doesn’t guarantee a claim payment, timeframe or premium saving.
“Daniel was great to deal with, quick responses and was able to offer very competitive options. Was also happy to provide advice on comparable options i had received. Highly recommend.”
“We have been using Daniel and his business for some time now, as our insurance needs have grown, the headaches regarding insurance haven’t, it’s always a hassle free interaction with any needs, be it costs or claims. Very very happy with Priority I durance brokers”
“Priority Insurance has been patient and helpful throughout the process of acquiring our insurance. Thanks again for the team to assist us,”
Verbatim Google reviews, shown with the reviewers’ own wording.
How it works
You don’t need to know every insurance term. Start with the facts about your work.
01
Your fit-outs, design role, crew, workshop and contracts.
02
We work out what insurers need to know and approach suitable markets.
03
Cover, limits, exclusions, excesses and premium, before you decide.
Daniel Ufer
Managing Director
Your broker
Daniel founded Priority and still looks after key accounts. He works closely with trades, construction and other blue-collar businesses, and our team works the same way.
Trades
Fit-out
Liability
PI
Qualifications
FAQs
Most start with Public Liability, tools and contract works, then add professional indemnity if they design, plus vehicles and a workshop package.
You may if you prepare drawings, specify finishes or take design-and-construct responsibility.
It is aimed at injury and damage to other people’s property. Check the wording for work in shared centres and after hours.
Yes. Insurers ask about subcontractors because they change your cover and premium. Some policies exclude claims from uninsured or undeclared subcontractors.
It matters most when you contract for the fit-out directly and need cover for the works under construction.
Not always. A private motor policy may not cover business use or a fit-out.
Before you start trading on your own. Work you do through your own business isn’t covered by an employer’s policy.
It depends on your fit-out types, design role, crew, turnover, tools, workshop, claims history and the covers you choose. A broker needs those details to give you an accurate quote.
Not sure what your business needs? Tell us how you work and we’ll take you through it.
Let’s talk about your work
New cover, a contract requirement or a review of what you have now. Every enquiry goes to a broker.
Call a broker
07 3103 2992
quotes@priorityib.com.au
Office
Level 7, 154 Melbourne Street, South Brisbane QLD 4101
General information only. Availability, limits, exclusions and premiums depend on your circumstances and the insurer. Submitting an enquiry doesn’t put cover in place.
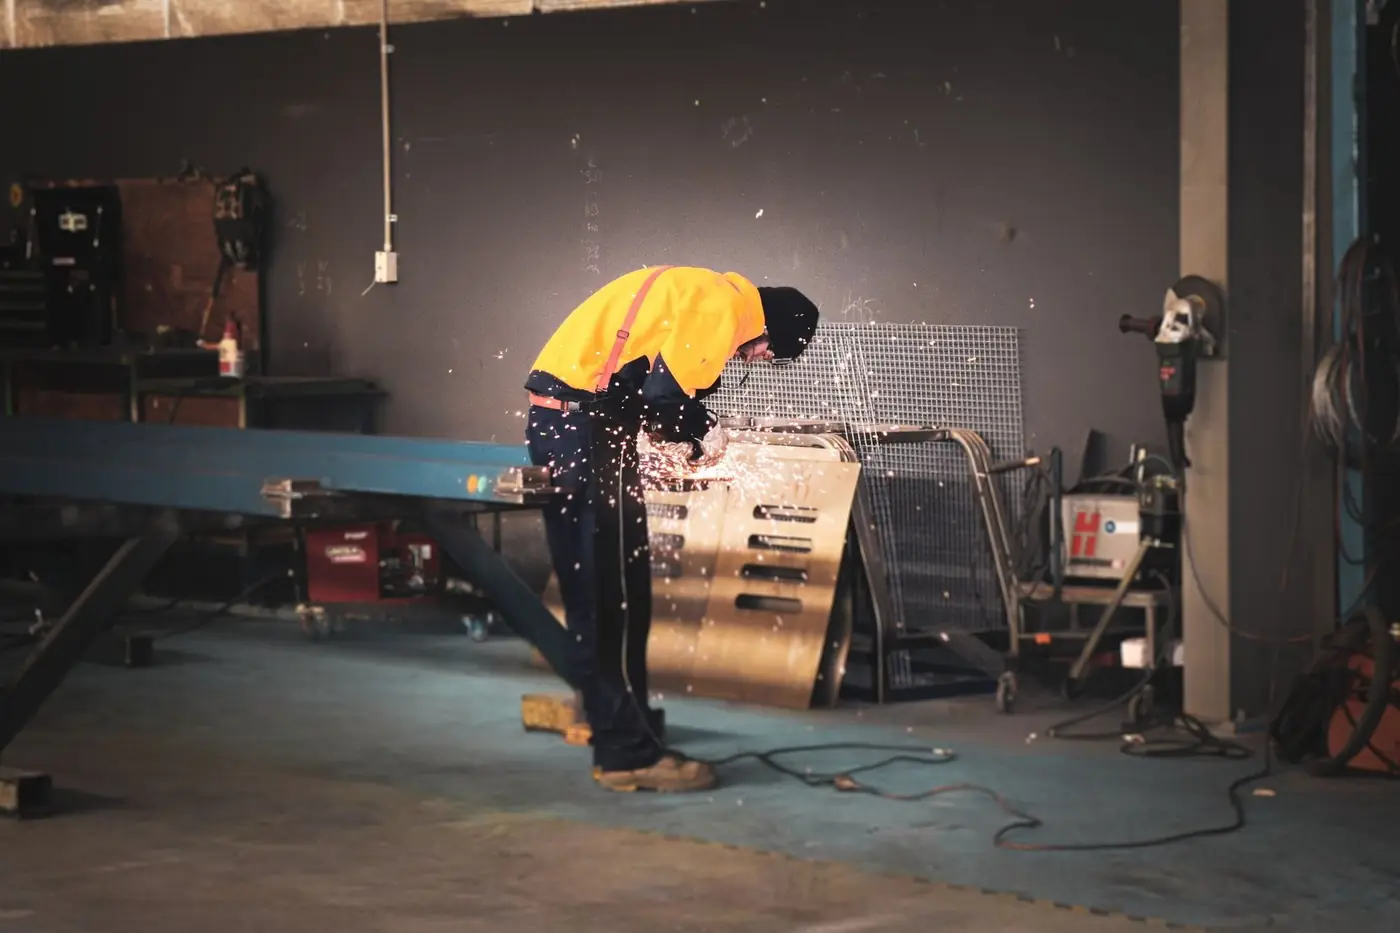
Photo credits: Top photo (cropped) by John Robert McPherson, CC BY-SA 4.0; On-site photo by John Robert McPherson, CC BY-SA 4.0. Via Wikimedia Commons.
You can leave the optional details blank and discuss them with your broker.
Submitting an enquiry doesn’t put insurance cover in place.
Prefer to talk? Call 07 3103 2992.